
The Quiet Accumulation Nobody Is Talking About
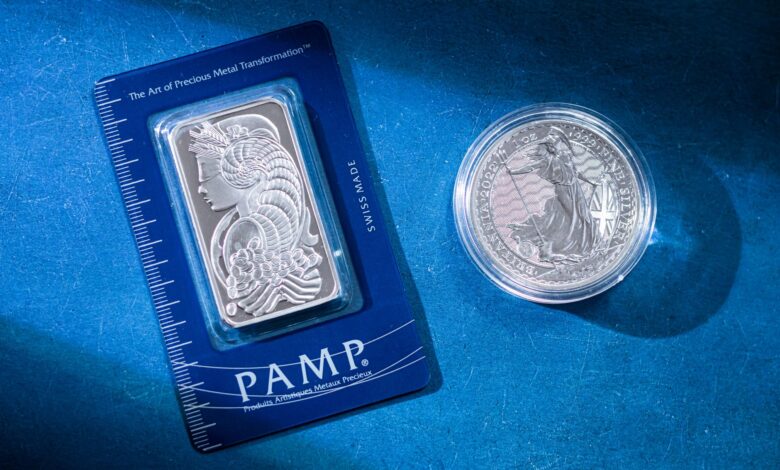
Silver royalty streams occupy a strange corner of the investment world – well understood by mining insiders, largely ignored by retail investors, and increasingly favored by family offices that prefer to build positions before a thesis becomes crowded. The structure is straightforward: a royalty company pays an upfront fee to a mining operation in exchange for the right to purchase a percentage of silver production at a fixed, below-market price for the life of the mine. The royalty holder never touches a shovel. They simply collect the spread between their contracted purchase price and the spot market price, indefinitely.
What makes this attractive to multigenerational wealth managers is the asymmetry of the arrangement. The royalty holder’s downside is capped at the initial capital outlay. The upside, however, stretches across decades of production, with no exposure to operating cost inflation, labor disputes, or permitting delays. Mining companies absorb all of that. The royalty holder sits upstream of the risk curve and downstream of the revenue.
Family offices have been moving into this space with little fanfare.
Why Silver, Why Now
Silver carries a dual identity that makes it particularly interesting at this moment. It is simultaneously a monetary metal – historically treated as a store of value alongside gold – and an industrial input with growing demand from solar panel manufacturing, EV battery components, and medical technology. That combination creates a demand profile that is harder to disrupt than pure industrial metals and less correlated to central bank sentiment than pure gold. For a family office trying to hedge across multiple economic scenarios, that duality is worth paying attention to.
The royalty stream model amplifies this appeal. Because royalty agreements are typically struck when a mining project needs development capital, the contracted purchase prices are often set years before a mine reaches full production. If silver spot prices rise – as they have across several periods in recent years – the spread between the contracted price and market price widens. The royalty holder captures that widening without any additional capital commitment. For portfolios already holding physical silver or silver ETFs, a royalty stream provides a structurally different form of exposure, one that generates cash flow rather than simply tracking price.
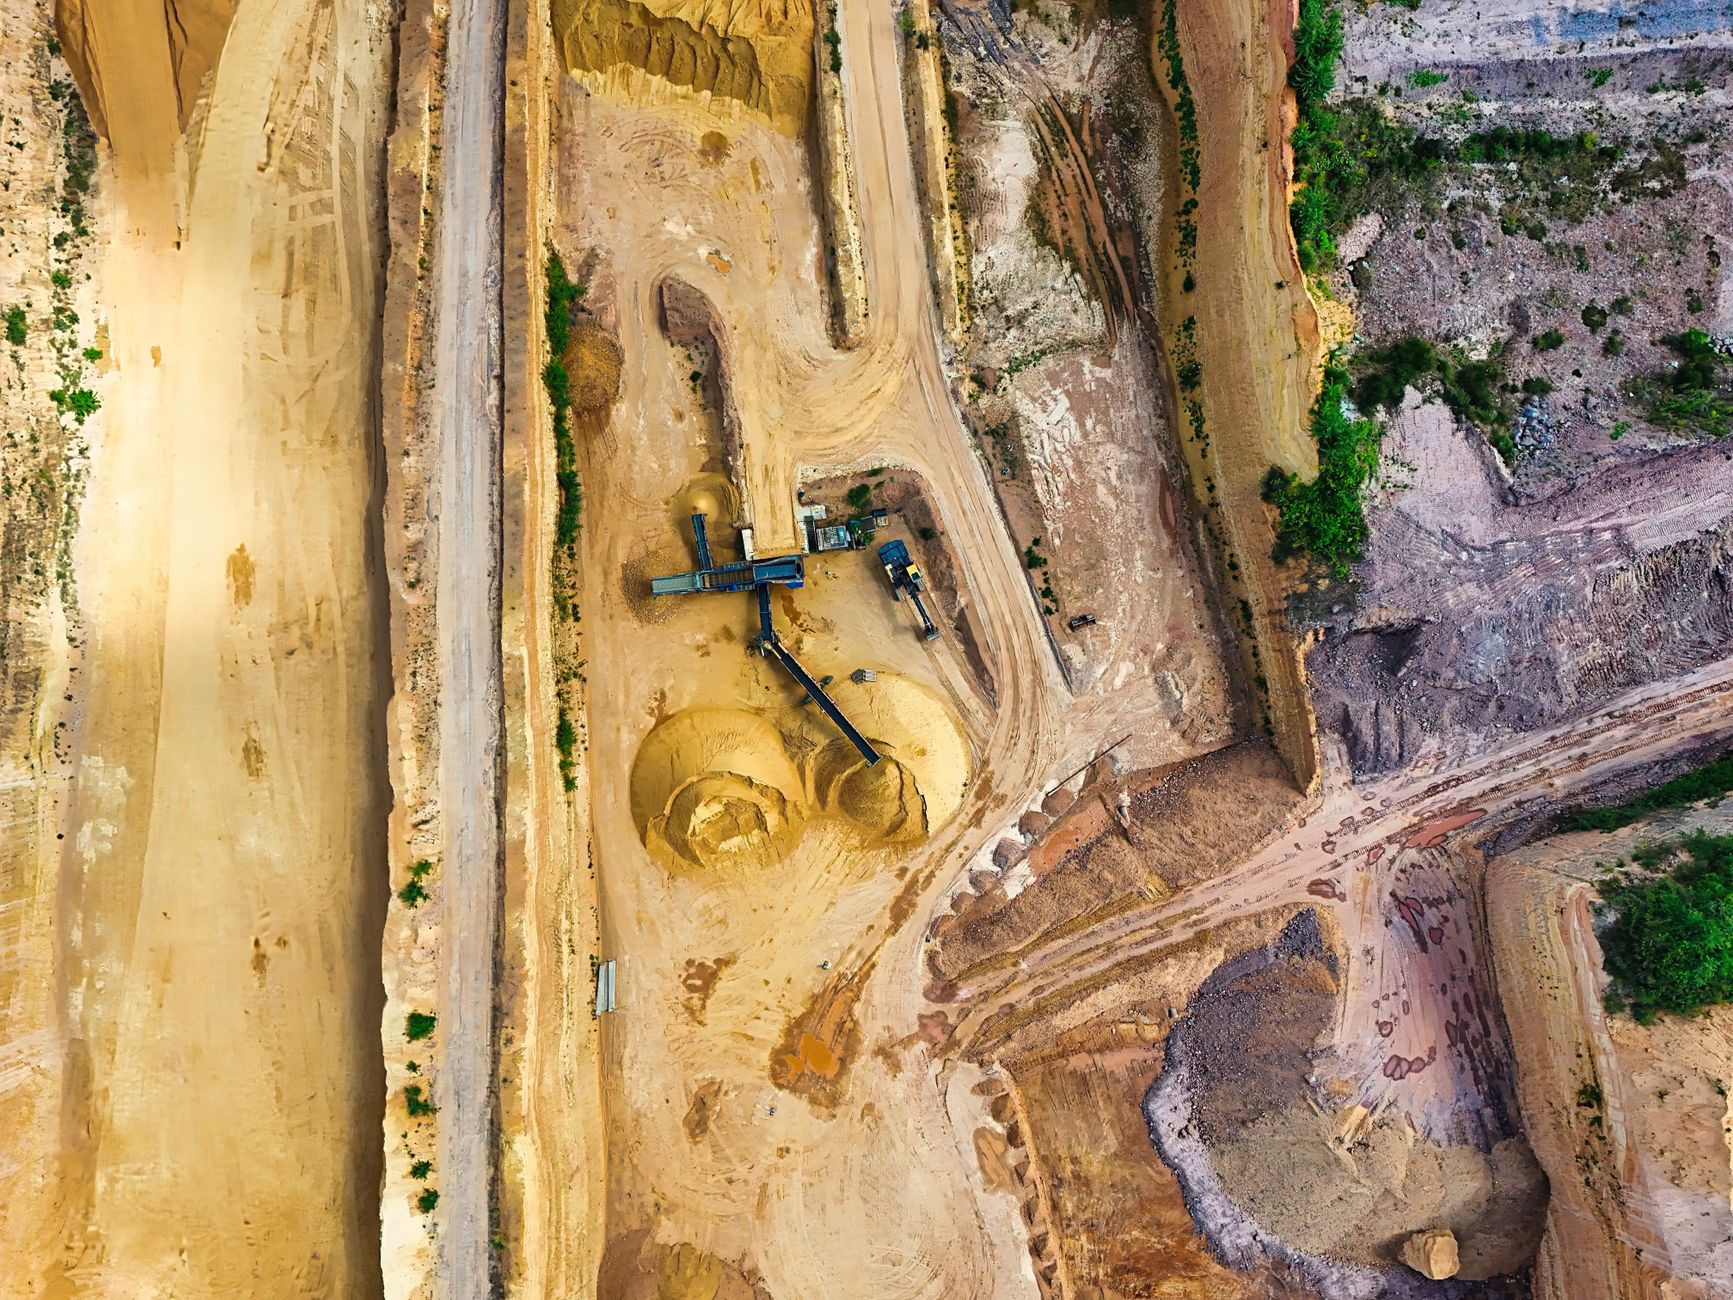
There is also a supply argument building quietly in the background. Silver is predominantly mined as a byproduct of copper, zinc, and lead operations. Primary silver mines are relatively rare, which means silver production is partly hostage to decisions made about base metal extraction. If base metal mining slows – whether due to regulatory pressure, energy costs, or commodity cycle downturns – silver supply tightens without any direct relationship to silver demand. Royalty holders with contracts on primary silver operations are insulated from that dynamic in a way that general silver investors are not.
How Family Offices Structure These Positions
Direct acquisition of royalty streams requires significant capital, deal access, and due diligence capacity that most individual investors cannot replicate. Family offices, particularly those managing assets for single ultra-high-net-worth families or small multi-family platforms, often have dedicated alternative investment teams that can evaluate the geological reports, production histories, and operator track records required to assess a royalty agreement properly. This is not a casual investment – it demands the same analytical rigor applied to private equity or real estate syndications.
Some family offices gain exposure through publicly traded royalty and streaming companies rather than direct agreements. This provides liquidity and diversification across multiple mine assets, though it introduces equity market correlation that pure royalty ownership avoids. The more sophisticated approach – and the one increasingly discussed in family office circles – involves co-investment alongside established royalty companies, taking a minority stake in specific stream agreements that the larger company originates and manages. This keeps deal overhead manageable while preserving direct asset exposure. Those interested in how similar structures apply to other metals can find context in the emerging interest around platinum group metal royalty streams, where the structural logic is nearly identical.
The holding period expectations for these positions are long – often ten to twenty years, aligned with the productive life of the underlying mine. This suits family offices with intergenerational mandates far better than it suits institutional investors with quarterly reporting pressures. A royalty stream that pays modest cash flows for the first three years before a mine reaches full capacity is a liability for a fund manager answering to limited partners; it is a feature for a family office building a portfolio meant to outlast its current principals.
The Risk Calculus
No investment structure eliminates risk entirely, and silver royalty streams carry specific vulnerabilities that family office teams need to account for before committing capital. Mine life estimates can be wrong – geological surveys are models, not guarantees, and a mine that was projected to produce for thirty years may face resource depletion, water access issues, or regulatory shutdown well before that horizon. The royalty holder collects nothing if the mine stops producing. Unlike debt holders in a mining company bankruptcy, royalty holders have limited legal recourse because the royalty is tied to production, not to company solvency. If the mine shuts down, the stream dries up regardless of what happens to the operator’s other assets.
Concentration risk is another consideration. A family office that allocates meaningfully to two or three royalty streams tied to mines in the same geographic region – say, Latin America or Central Asia – has inadvertently taken a political and regulatory bet. Nationalization of mining assets, sudden royalty tax changes imposed by host governments, or environmental permit cancellations have all occurred in major silver-producing regions within the past decade. Geographic diversification across a royalty portfolio is not optional; it is the basic structural discipline that separates a thoughtful allocation from a speculative position dressed up in conservative language.
What keeps family offices in this space despite those risks is the fundamental economics of the royalty model: the initial capital deployment is fixed, the cash flow extends across decades, and the inflation hedge is embedded in the structure rather than dependent on active management. Silver prices rising ten percent means royalty holders earn more with zero additional effort or cost. That is a rare feature in a world where most yield-generating assets require ongoing management attention, reinvestment decisions, and exposure to operating leverage that can cut both ways.
The family offices deepest into this strategy are not betting on a silver price spike next quarter. They are betting that silver will matter more in twenty years than it does today – and that owning the right to buy it cheaply, forever, is worth more than anyone currently priced it at.