Family Offices Quietly Accumulate Stakes in Nickel Laterite Streaming Agreements

The Quiet Accumulation
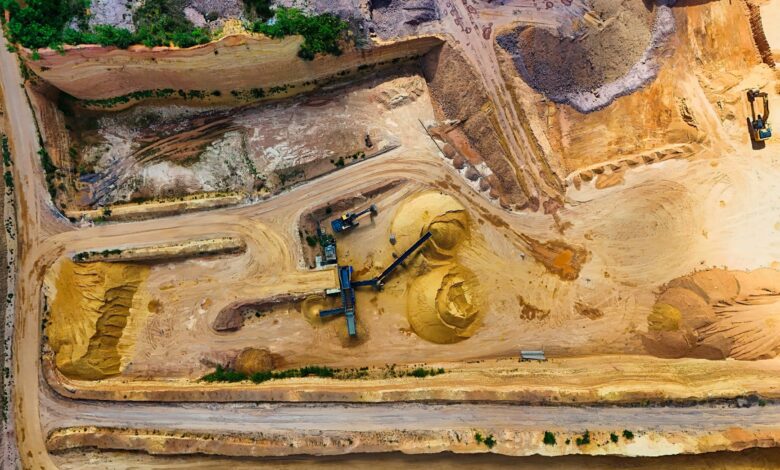
Nickel laterite streaming agreements are not the kind of asset that shows up in press releases or quarterly investor calls. They exist in the less visible corridors of commodity finance, where the deal terms are negotiated privately and the capital flows without fanfare. That is precisely why family offices – institutions built around privacy, long time horizons, and direct deal access – have started treating them as a meaningful allocation.
A streaming agreement, in its basic structure, gives an investor the right to purchase a set volume of metal production at a predetermined price in exchange for upfront capital provided to the mining operator. Nickel laterite deposits, which account for a growing share of global nickel supply, have become the focus of this financing model as traditional mining lenders grow more cautious about long-duration commodity exposure. Family offices are stepping into that gap, and doing so with minimal visibility.
Why Nickel Laterite, and Why Now
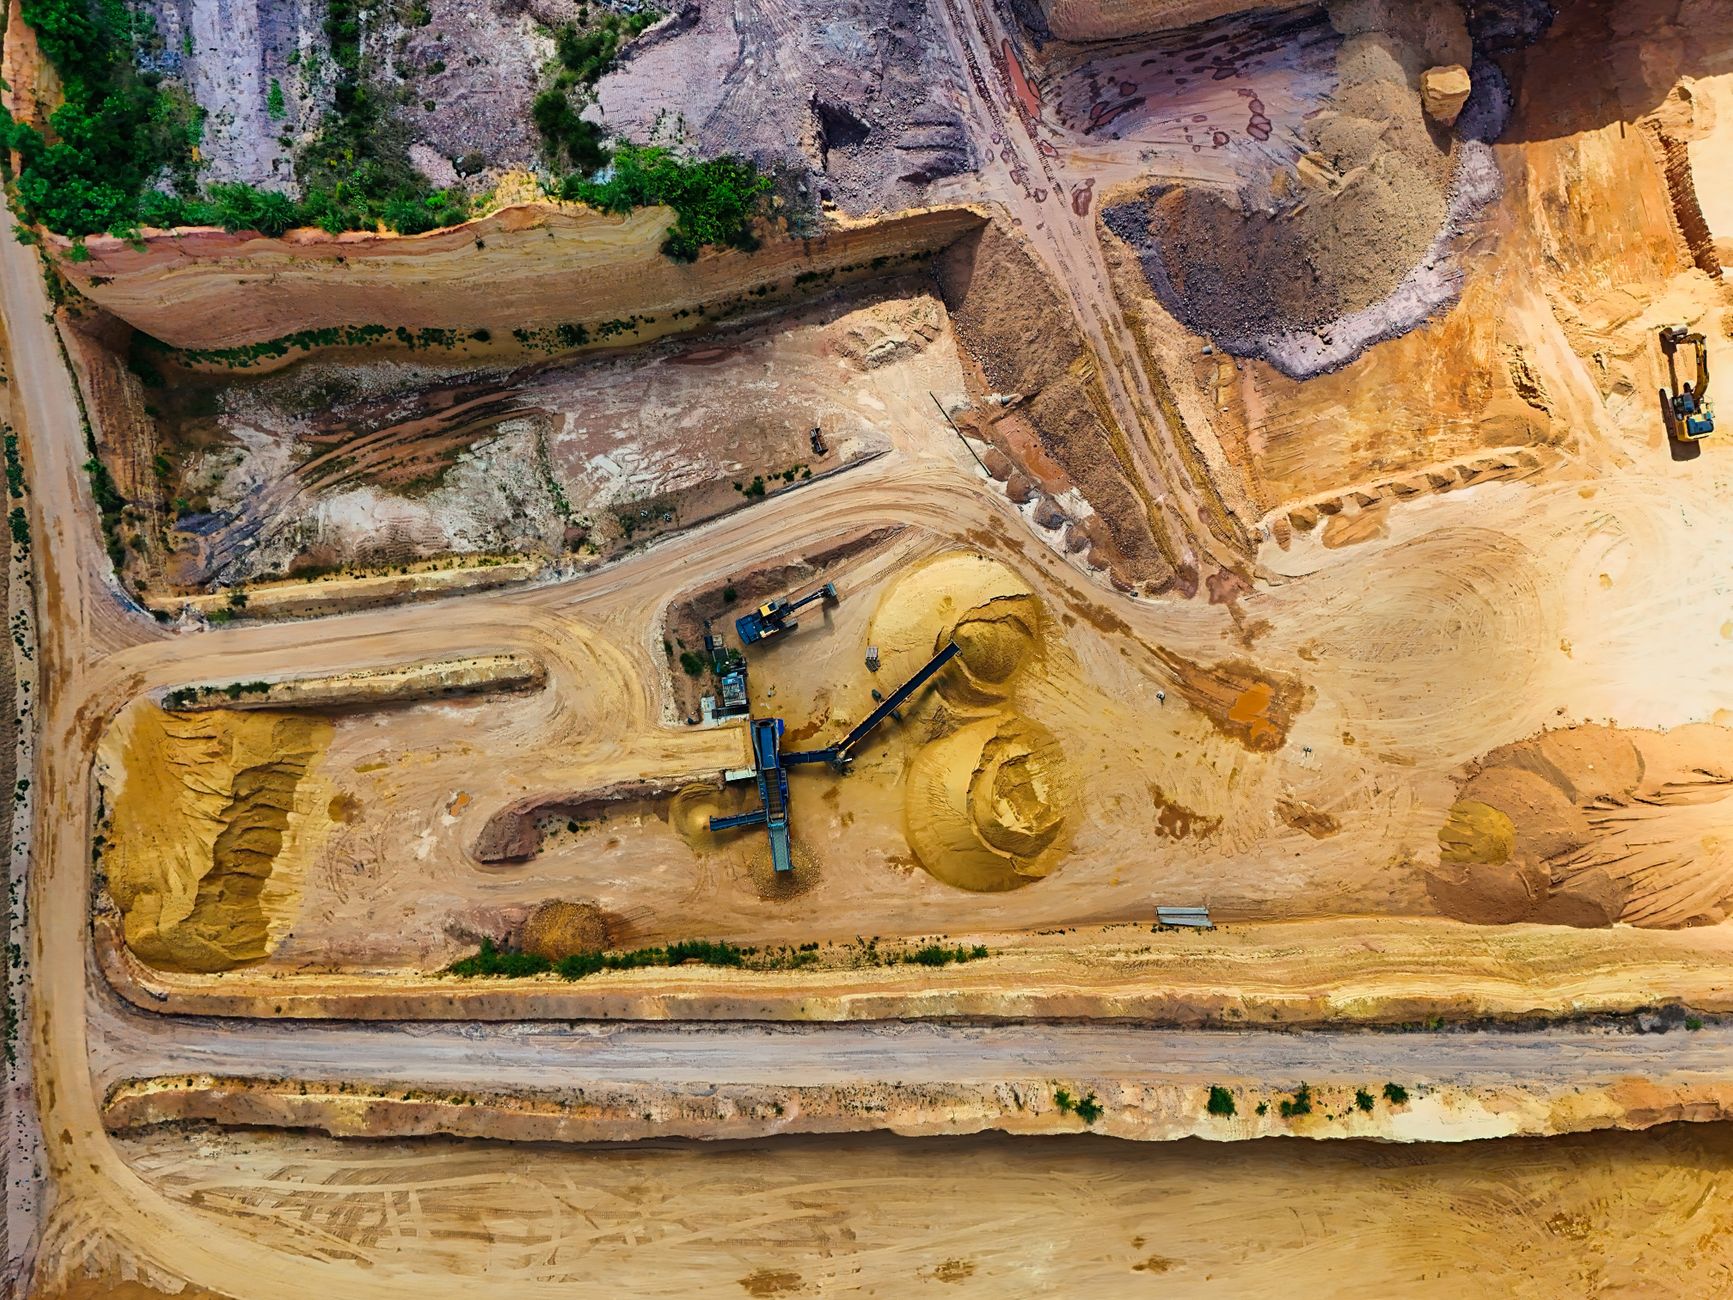
Nickel exists in two primary geological forms: sulfide deposits and laterite deposits. Sulfide deposits have historically been favored because they are cheaper to process, but the accessible high-grade sulfide reserves are increasingly depleted. Laterite deposits, which are formed through the weathering of nickel-bearing rocks near the earth’s surface, now account for the majority of the world’s identified nickel resources. Processing them is more energy-intensive and capital-demanding, but the scale of the resource base makes them impossible to ignore for investors thinking about battery supply chains over a 10- to 20-year window.
The economics of nickel laterite projects create a natural opening for streaming finance. These projects require large upfront capital commitments before meaningful production begins, and the lead times between investment and cash flow can stretch across several years. Conventional bank financing is often reluctant to extend that kind of patience without collateral structures that many junior and mid-tier mining companies cannot provide. A streaming deal sidesteps that problem by offering the mining company immediate liquidity in exchange for a long-dated production commitment – a structure that suits both sides when executed properly.
Family offices are drawn to this structure for reasons that go beyond yield. The combination of a fixed purchase price and a long-duration production stream creates an asset that behaves differently from public equity, public credit, or even traditional commodity futures. The return profile is tied to the spread between the contracted purchase price and the prevailing spot price of nickel over the life of the agreement. When nickel prices rise – as they have during periods of accelerating battery manufacturing demand – the economics of an existing streaming position improve dramatically without requiring any additional capital deployment.
How Family Offices Are Accessing These Deals
Direct access to streaming agreements at the deal origination stage has historically been dominated by a small number of specialized royalty and streaming companies. What has changed recently is that some family offices with dedicated natural resource teams are co-investing alongside those platforms, taking minority participation in streaming packages that the lead arranger then manages operationally. This structure gives the family office exposure to the underlying commodity economics without requiring it to build the due diligence infrastructure that primary deal origination demands.
A parallel trend involves family offices funding newer streaming platforms directly – providing seed capital or working capital to emerging royalty companies that then deploy those funds into laterite streaming agreements. This is a step removed from the underlying asset but preserves the upside economics while outsourcing origination risk. It mirrors the approach that family offices have used to build exposure to carbon black offtake rights, where indirect access through a structured vehicle reduces operational complexity while maintaining commodity-linked return potential.
The Risk Architecture Nobody Talks About Publicly
Nickel laterite streaming is not a clean trade. The production risk is real – laterite processing, particularly through high-pressure acid leaching, is technically demanding, and projects have a documented history of cost overruns and commissioning delays. An investor locked into a streaming agreement tied to a project that underproduces gets less metal than the model assumed, which compresses returns in ways that are difficult to hedge. Sophisticated family offices are addressing this by structuring agreements with minimum delivery guarantees and by insisting on independent technical review of the processing facility before capital is committed.
Price risk runs in both directions. The same nickel price volatility that makes streaming positions attractive during bull markets can erode the real value of a fixed purchase price during extended periods of oversupply. Nickel has experienced sharp downward price movements historically, and the rapid expansion of Indonesian nickel processing capacity has added a structural supply overhang that keeps some commodity analysts cautious about the long-term price floor. Family offices entering streaming agreements during a price trough are arguably better positioned than those who committed capital at cycle highs.
Jurisdiction is the variable that most often determines whether a well-structured deal survives its full term intact. Nickel laterite deposits are concentrated in a handful of countries, including Indonesia, the Philippines, and parts of Central Africa, where resource nationalism, royalty renegotiations, and permitting instability have disrupted projects that looked financially sound on paper. Family offices with experience in direct commodity investments have learned to weight political risk heavily, often preferring lower-grade assets in stable jurisdictions over higher-grade deposits in politically volatile ones. The extra processing cost of a less concentrated ore body is a known expense; an unexpected export ban or production curtailment is not.
What makes this allocation genuinely interesting from a portfolio construction standpoint is its low correlation to conventional asset classes. Nickel laterite streaming agreements do not trade on public markets, their valuations are not marked daily, and their return drivers are tied to physical production and commodity prices rather than equity sentiment or credit spreads. For family offices managing multigenerational wealth, that illiquidity is not a drawback – it is a feature, because it forces a holding discipline that public market investments rarely impose. The question worth asking is whether the current window of deal access, which exists partly because larger institutional capital has not yet moved aggressively into this niche, will still be open in three years, or whether rising interest in battery metals finance will compress the terms that make these agreements attractive in the first place.
Frequently Asked Questions
What is a nickel laterite streaming agreement?
It is a contract where an investor provides upfront capital to a mining operator in exchange for the right to buy a set volume of nickel production at a fixed price over a long period.
Why are family offices interested in nickel laterite streams specifically?
The structure offers commodity-linked returns with low correlation to public equity and credit markets, and nickel laterite deposits hold a large share of global nickel resources tied to battery supply chains.