
The Quiet Pivot Toward Copper Streaming
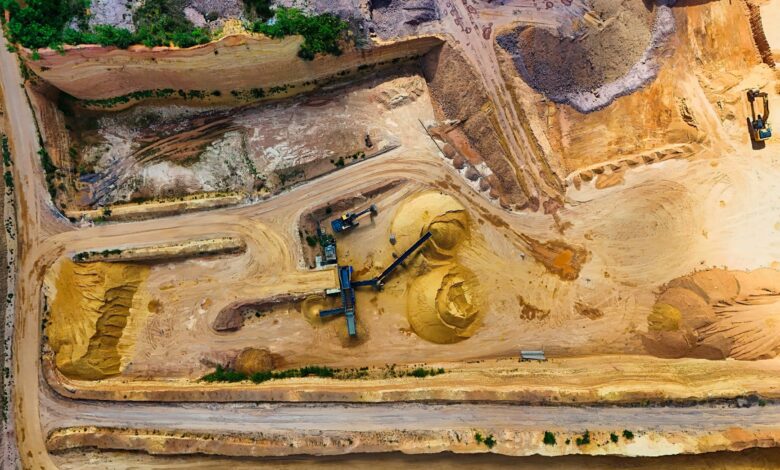
Sovereign wealth funds, long associated with equities, real estate, and government bonds, are quietly repositioning a slice of their portfolios toward an obscure but increasingly attractive corner of commodities finance: copper concentrate streaming agreements. The shift is driven by copper’s accelerating role in electrification infrastructure and the structural advantages that streaming deals offer over direct mine ownership.
Why Streaming Agreements Appeal to Long-Duration Capital
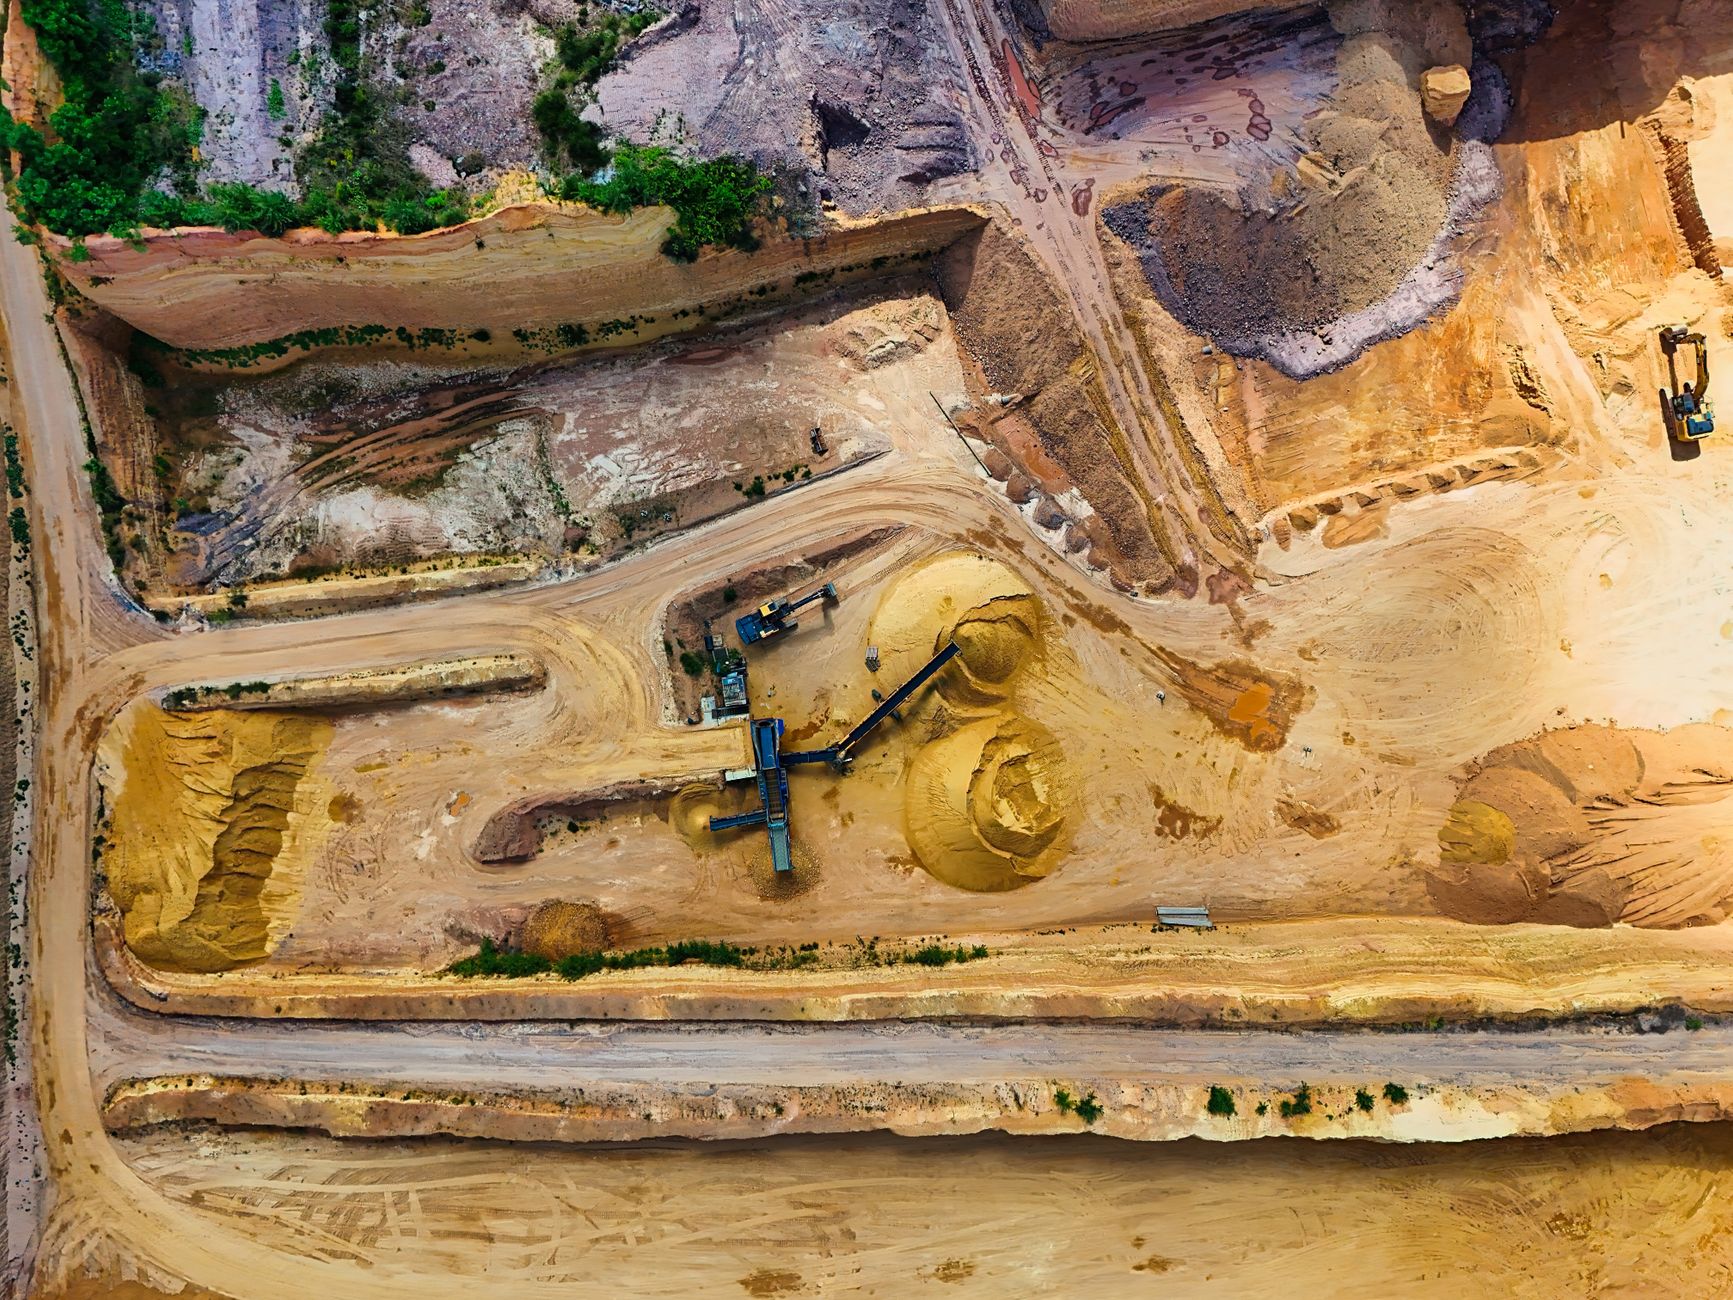
A streaming agreement, at its core, is a financing arrangement where an investor provides upfront capital to a mining operation in exchange for the right to purchase a fixed percentage of future metal production – typically at a steep discount to spot prices. The streaming company or fund does not operate the mine; it simply collects a share of output over decades. For sovereign wealth funds managing capital across 20- and 30-year horizons, that duration is a feature, not a liability.
Copper concentrate specifically – the partially processed ore form shipped from mine to smelter – sits at an earlier point in the value chain than refined copper cathode. Streaming agreements tied to concentrate production can be structured at lower entry costs than finished-metal streams, and they tend to carry slightly higher yields to compensate for the processing risk. For large funds hunting yield in a compressed fixed-income environment, that spread is worth the added complexity.
The appeal is also structural. Unlike equity stakes in mining companies, streaming contracts are insulated from many of the operational headaches that make mining investments volatile – labor disputes, environmental fines, management turnover. The streaming holder simply receives metal or cash equivalents based on a pre-agreed formula. When a mine hits problems, the streaming partner’s position is usually senior to equity and subordinate only to secured debt, putting it in a relatively protected spot in the capital stack.
Several sovereign funds in the Gulf Cooperation Council and Southeast Asia have been exploring this structure through dedicated commodity finance mandates. The Norwegian Government Pension Fund’s well-publicized commodity exclusion policies have pushed some peer funds in the opposite direction – toward structured commodity finance rather than direct commodity exposure – as a way to maintain access to the energy transition without holding extractive company shares directly.
Copper’s Role Makes the Timing Deliberate
Copper demand projections tied to electric vehicle production, grid expansion, and data center buildout have made the metal a focal point for funds with explicit energy transition mandates. Unlike lithium or cobalt, which face substitution risk as battery chemistry evolves, copper has no credible near-term substitute in electrical wiring and motor windings. That makes long-dated copper streaming contracts an attractive way to get structural exposure to electrification without betting on any single technology stack.
The concentrate streaming market has historically been dominated by specialized royalty and streaming companies – businesses built specifically around this model. But sovereign wealth funds bring something those companies cannot easily match: virtually unlimited patient capital and the ability to hold positions through commodity downturns without facing margin calls or investor redemptions. That staying power makes them formidable counterparties for mining companies seeking long-term financing commitments.
Mining companies in Chile, Peru, the Democratic Republic of Congo, and Zambia – which collectively account for the majority of global copper concentrate supply – have been increasingly receptive to sovereign fund capital. Traditional project finance from commercial banks has become more restricted as environmental, social, and governance screening tightens lending criteria. Sovereign funds, particularly those with bilateral development relationships with copper-producing nations, can step into that financing gap with terms that work for both sides.
The royalty and streaming space has previously attracted significant institutional interest from family offices and endowments. Family offices accumulating platinum group metal royalty streams have laid groundwork that sovereign funds are now following, applying similar logic to a metal with broader industrial and policy relevance. The difference in scale is considerable – where a family office might commit tens of millions to a single streaming arrangement, a sovereign fund can structure deals in the hundreds of millions, often providing the entire upfront payment a mine needs to proceed through expansion or development.
Pricing dynamics add another layer of appeal. Copper concentrate streaming deals are typically priced relative to London Metal Exchange benchmarks, with the discount to spot locked in contractually. If copper prices rise – as many forecasts suggest they will as supply tightens against rising demand – the streaming holder benefits from a widening margin between its locked purchase price and the market value of metal it receives. That asymmetry, where downside is cushioned by the discount structure and upside is uncapped, is precisely the kind of return profile long-horizon institutional capital seeks.
Structural Challenges Still Linger
The path is not without friction. Copper concentrate streaming agreements require significant legal and technical due diligence – assessing ore grade consistency, processing yield estimates, smelter offtake chains, and sovereign risk in host countries. Funds without internal commodity expertise have been building out specialist teams or partnering with established streaming platforms to co-invest, trading some return for reduced execution risk. Regulatory scrutiny in some jurisdictions also adds friction; a sovereign wealth fund taking a long-dated production interest in a strategically important mine can trigger national security reviews, particularly in countries that have designated critical mineral assets as matters of state interest.
What makes this moment distinct is that the competitive field is still relatively uncrowded. The major streaming companies have finite balance sheets; commercial banks are pulling back; and equity markets have been unreliable for junior miners trying to fund expansion. Sovereign funds entering this space now are doing so before the structure becomes mainstream, which means they still have pricing power when negotiating the discount rates and production percentages at the heart of these contracts. Whether that window stays open as more capital chases fewer quality assets is the question copper miners and their new sovereign backers are quietly watching.
Frequently Asked Questions
What is a copper concentrate streaming agreement?
It’s a financing deal where an investor provides upfront capital to a mining operation in exchange for the right to buy a percentage of future copper concentrate production at a pre-set discount to market prices.
Why are sovereign wealth funds interested in streaming deals rather than mining stocks?
Streaming agreements offer long-duration returns, reduced operational risk, and senior-like positioning in the capital stack – better suited to funds with 20-30 year investment horizons than volatile mining equities.