
The Quiet Accumulation
Phosphate mine royalty streams have never been glamorous. They sit in the unglamorous middle of the agricultural supply chain – between the extraction of rock phosphate from the ground and the fertilizer that eventually reaches a farm field. But that obscurity is precisely why a growing number of family offices are moving into the space with unusual conviction. These aren’t speculative bets on commodity prices. They are structured, long-duration income positions that pay regardless of who operates the mine or what spot phosphate trades for on any given Tuesday.
A royalty stream, in the simplest terms, is the right to receive a percentage of revenue – or a fixed fee per ton – from a producing mine, without bearing the operational costs of running it. The royalty holder gets paid when rock comes out of the ground. The mining company handles labor, equipment, environmental compliance, and every other operational headache. For capital that needs quiet, durable income over decades, the math is straightforward.
Family offices, which manage the private wealth of ultra-high-net-worth families and typically operate without the quarterly performance pressures that constrain institutional funds, are particularly well suited to this kind of asset.
Why Phosphate, Why Now
Phosphorus is not substitutable. Unlike nitrogen, which can be synthesized from atmospheric gas through industrial processes, phosphorus must be mined from finite rock deposits. Global food production depends on phosphate fertilizers, and the geographic concentration of high-quality reserves – with Morocco holding the largest share by a considerable margin – means that supply disruptions have outsized consequences. That structural scarcity is not a short-term story. It plays out over generations, which aligns neatly with the multi-generational time horizons that family offices often manage toward.
The surge in demand for food security infrastructure following years of agricultural commodity volatility has pushed more attention toward upstream inputs. Phosphate prices spiked sharply in recent years before retracing, and that volatility created an opening: royalty streams tied to operating mines could be acquired at valuations that did not fully price in the long-run supply constraint. Family offices with patient capital and the ability to move quickly on private deals – without committee approval cycles or public market liquidity requirements – were positioned to take advantage of that window before it closed.
There is also a portfolio construction logic at work. Royalty streams generate income that is indexed to production volume rather than to financial markets. They have low correlation to equities and bonds. For family offices managing multigenerational wealth, that kind of uncorrelated income is worth paying a premium for. The phosphate angle adds a commodity exposure that many wealthy families lack, not through direct commodity trading but through a more defensive, income-producing structure.
How These Deals Get Structured
The mechanics of a phosphate royalty acquisition vary, but the most common structure involves purchasing an existing royalty from a prior landowner, a streaming company, or occasionally from the mining operator itself in exchange for upfront capital. The family office pays a lump sum and receives contractual rights to a percentage of gross revenue or a per-ton royalty for the life of the mine – sometimes with minimum payment clauses that protect income during production slowdowns. These agreements are often senior to the equity of the mining company, meaning royalty holders get paid before shareholders see a distribution.
Some family offices are going further, acquiring royalty portfolios rather than single-stream positions. A portfolio of four or five royalties across different mines in different jurisdictions substantially reduces the risk that one mine closure or permitting dispute wipes out the income stream. This approach mirrors what family offices have done in other natural resource royalty categories, where diversification across sites and jurisdictions has become standard practice for managing concentration risk. The deal sizes tend to run from the low millions into the tens of millions, putting them below the threshold where large institutional investors compete aggressively but well above what most retail investors can access.
Legal structure matters enormously in this space. Royalty rights need to be clearly defined in the underlying land agreements, and the enforceability of those rights across state or national jurisdictions requires careful legal diligence. A royalty tied to a mine in a country with unstable property rights or weak contract enforcement is a fundamentally different instrument than one tied to an operating mine in the American West or Canada, even if the headline yield looks similar. Family offices that have moved into this space successfully tend to have legal and mineral rights expertise either in-house or through long-standing advisory relationships.
The Risk Side Nobody Talks About Enough
Mine depletion is the most obvious risk, and royalty buyers price it in through reserve life estimates – but those estimates are only as good as the geological surveys they are based on, and surveys can be wrong. A mine projected to produce for 40 years might encounter unexpected geological complexity that limits economic extraction at year 15. At that point, the royalty stream shrinks or disappears with little recourse for the royalty holder. Unlike equity investors, royalty holders generally cannot influence operational decisions or push management to improve recovery rates.
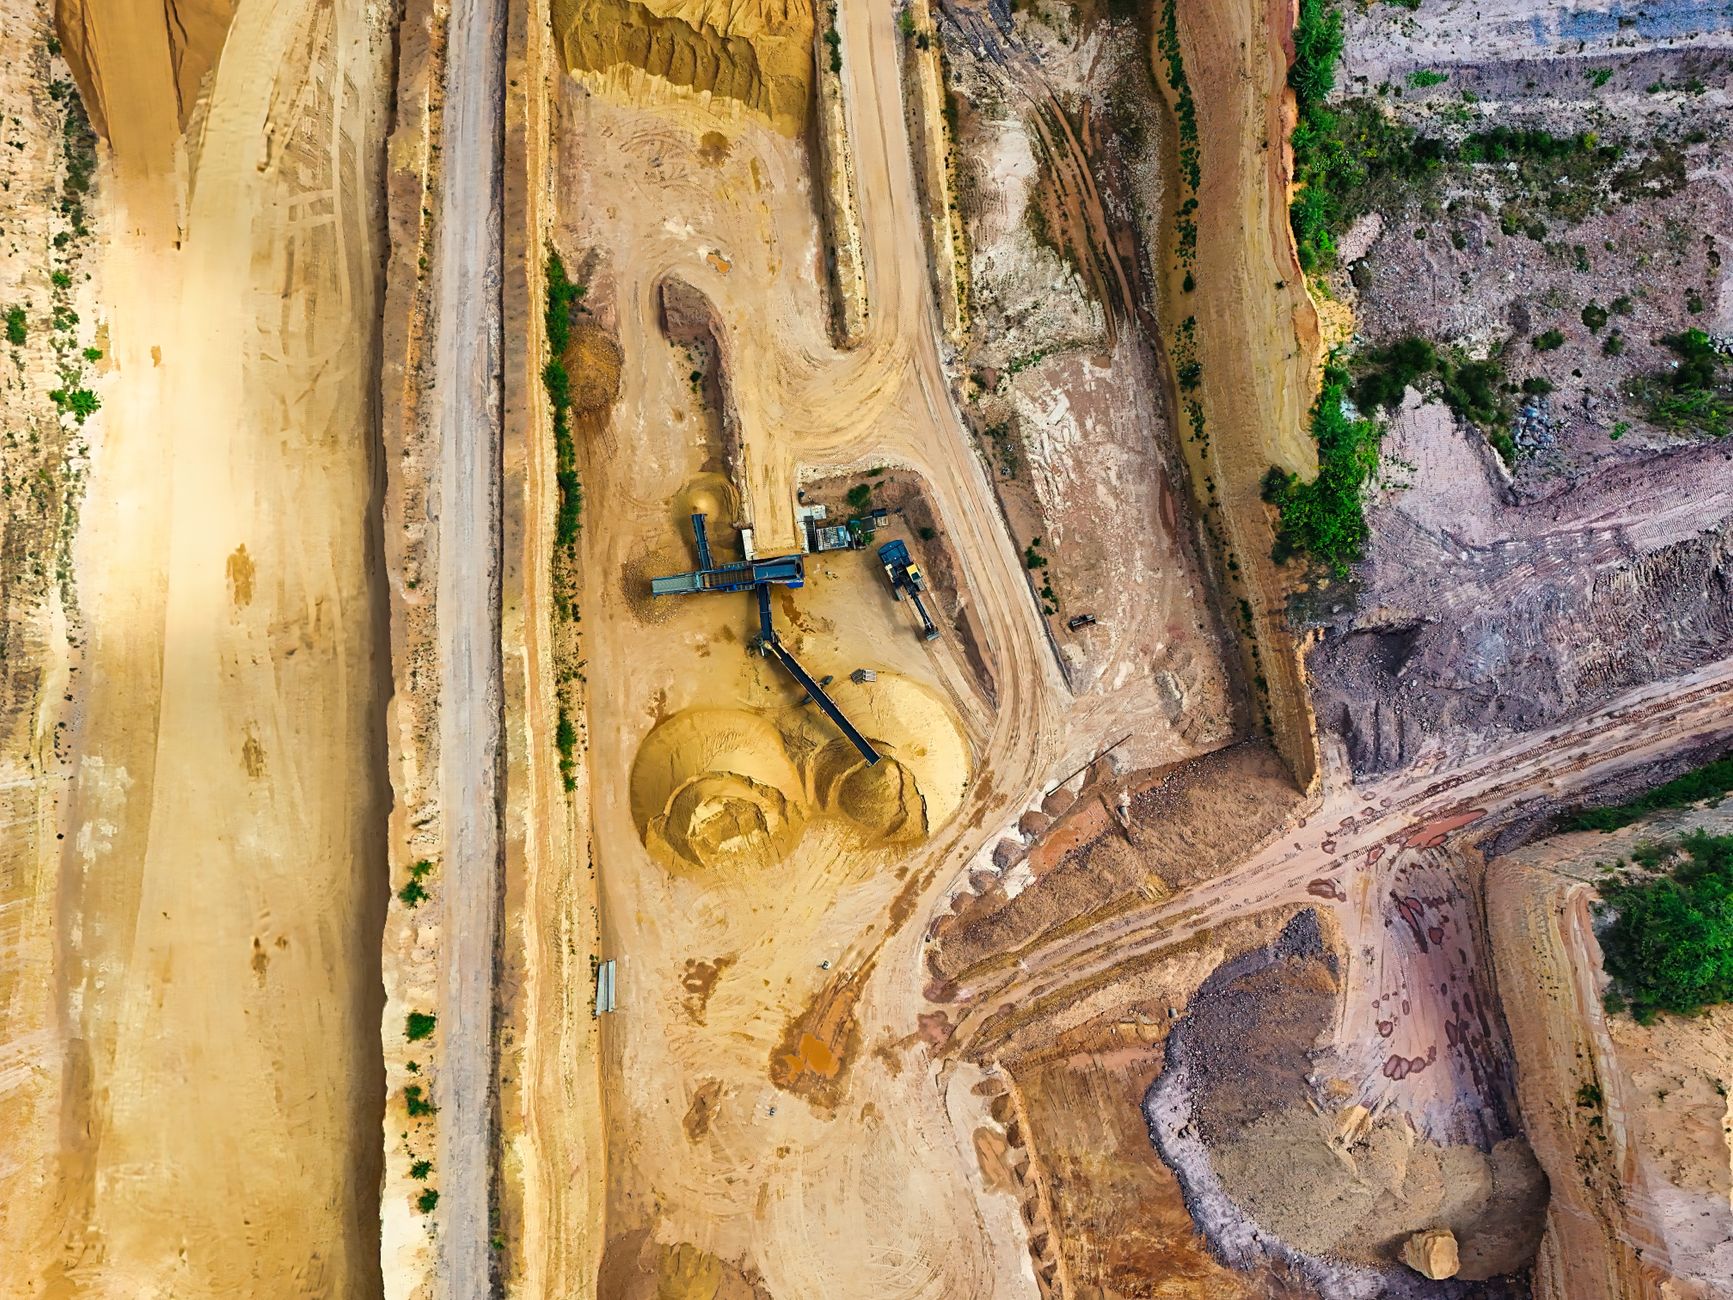
Regulatory and environmental risk sits right behind depletion risk on the list of concerns. Phosphate mining is water-intensive and generates significant waste – particularly phosphogypsum, a radioactive byproduct that requires careful management. Tightening environmental regulations could increase costs for mining operators to the point where some operations become uneconomical, triggering curtailment or closure. The royalty holder, protected from operating costs, is not protected from zero production. A mine that shuts down generates no royalties, regardless of how well the underlying agreement is drafted.
Commodity price cycles add a third layer of complexity. While royalty structures insulate holders from operating costs, revenue-based royalties still move with the price of phosphate – and phosphate can be volatile. A sustained price downturn might not kill a royalty stream, but it will reduce the absolute dollar income even if production volumes hold steady. Family offices underwriting these deals on the basis of peak-cycle phosphate prices would be taking a different risk than those stress-testing against trough pricing – and the difference between those two approaches can be the difference between a sound investment and a long, painful wait for a promised income that never quite materializes at the projected level.