
The Quiet Pivot Toward Precious Metal Streams
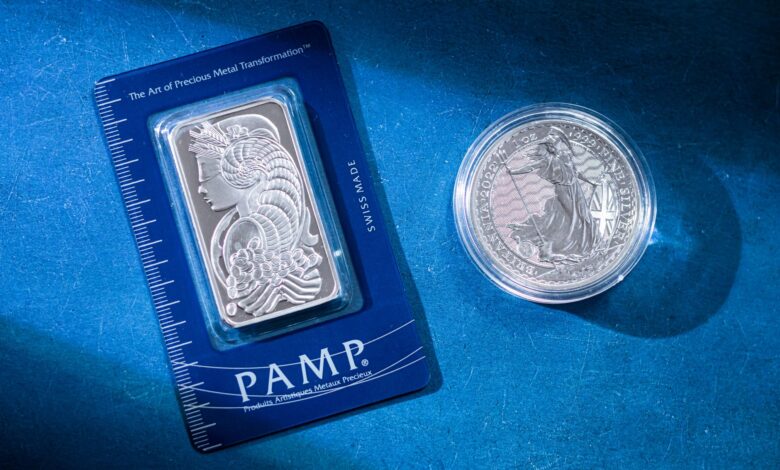
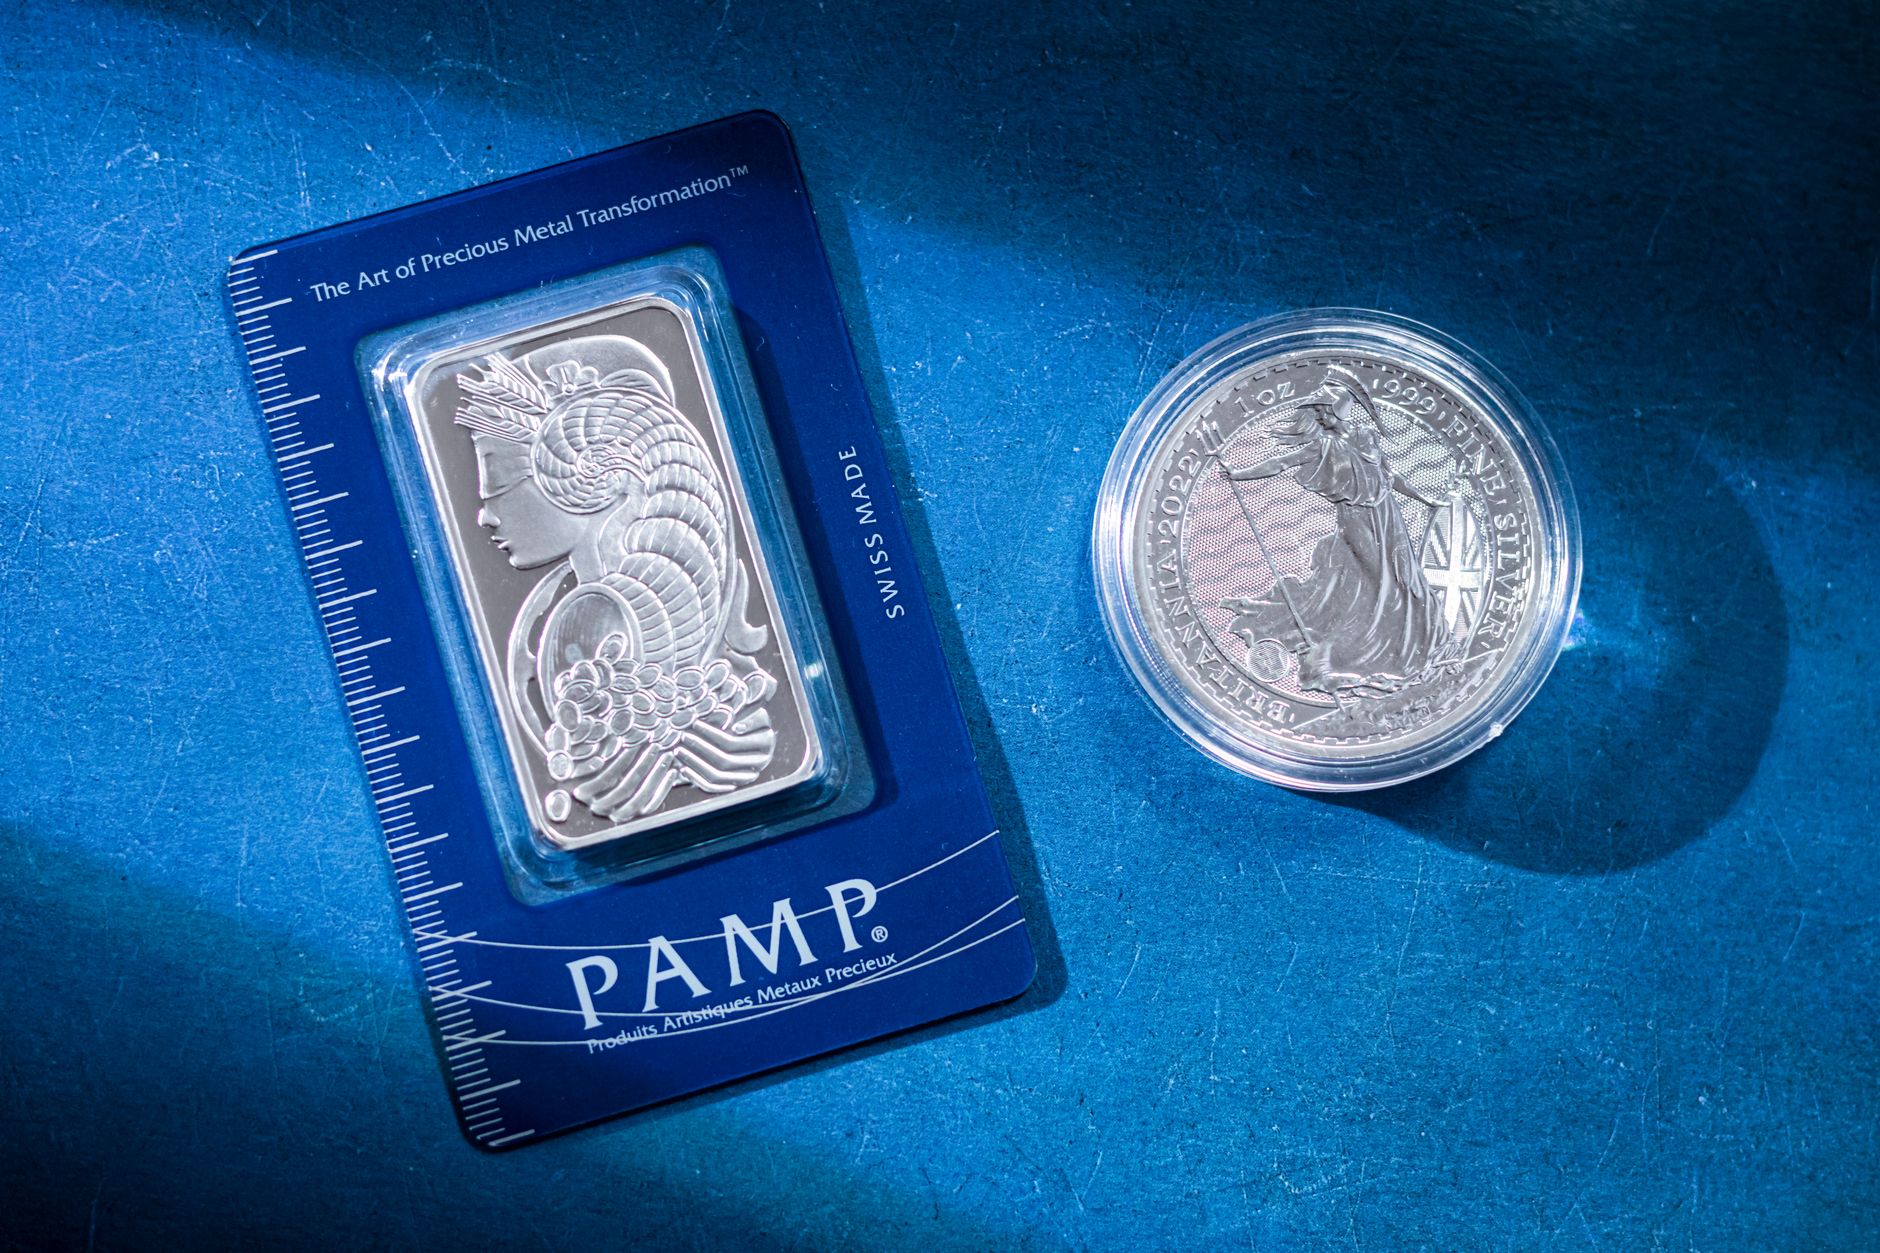
Silver streaming agreements have long been a tool favored by junior mining companies needing upfront capital and larger commodity investors seeking predictable metal exposure without the operational headaches of running a mine. The structure is straightforward: a streaming company pays an upfront fee to a miner in exchange for the right to purchase a set volume of silver at a fixed, below-market price for the life of the mine. What has changed recently is who is sitting on the streaming side of that table.
Pension funds – traditionally anchored in public equities, government bonds, and core real estate – have begun building quiet exposure to these agreements, either by acquiring stakes in established streaming companies or by participating directly in bespoke royalty and stream structures arranged through private credit and infrastructure channels. The shift is gradual, but it is deliberate, and it carries real implications for how institutional capital interacts with the silver market going forward.
Why Silver Streams Appeal to Long-Duration Investors
The appeal is structural. Silver streaming agreements generate cash flows that are tied to commodity prices but insulated from the cost inflation that typically erodes mining margins. Because the streaming company’s purchase price is locked in – often at a fraction of spot – even a flat silver price environment produces a healthy spread. For a pension fund managing liabilities that stretch thirty or forty years into the future, that kind of durable, embedded margin is more attractive than a straightforward commodity position where costs and revenues move in the same direction.
Silver also carries a dual demand profile that pure gold exposure does not. Industrial demand – concentrated in solar panel manufacturing, electronics, and medical devices – provides a floor that is relatively uncorrelated with financial market sentiment. When investor demand for precious metals softens, industrial consumption tends to persist or even grow, particularly as photovoltaic installation targets continue expanding globally. A streaming agreement capturing silver from a long-life polymetallic mine can therefore hold its value across a wider range of economic scenarios than most fixed-income alternatives currently available at comparable yield levels.
Inflation sensitivity is the third factor driving interest. Pension funds with inflation-linked liabilities need assets that can keep pace when purchasing power erodes. Physical silver holds that quality in theory, but physically storing metal creates custody costs, insurance obligations, and liquidity friction. A streaming agreement sidesteps all of that – the fund captures silver’s inflation-tracking characteristics through contractual cash flows rather than warehouse receipts, and those flows can be structured to pass through quarterly, fitting neatly into actuarial models. This family of royalty and stream structures is drawing similar attention from other institutional pools, including family offices building positions in helium royalty streams for comparable inflation-protection reasons.
How Pension Funds Are Getting In
Direct participation in a streaming deal requires scale, legal sophistication, and a willingness to underwrite mining counterparty risk – a skill set most pension fund internal teams do not maintain. The practical entry point for most funds has therefore been through private markets vehicles: closed-end funds, co-investment sleeves, or separately managed accounts run by specialist alternative asset managers who originate and structure the stream agreements, then bring institutional capital in at the fund level. This creates a layer of fee drag, but it also provides underwriting expertise and portfolio diversification across multiple stream agreements and multiple mining jurisdictions.
A smaller number of larger public pension funds have taken a more direct route, acquiring minority equity positions in publicly listed streaming and royalty companies. These companies trade on major exchanges and offer daily liquidity, but they also carry equity market correlation that pure stream exposure would not. The tradeoff is accessibility versus purity of the underlying cash flow. Funds prioritizing liability matching tend to prefer the private vehicle route; those with shorter liquidity windows or more flexible investment policy statements find the listed equity route easier to execute within existing frameworks.
The Risks That Don’t Make the Pitch Deck
Streaming agreements look elegant on paper, but they carry a specific category of risk that institutional investors accustomed to bonds or listed equities sometimes underestimate: mine-life optionality. A streaming agreement is only as durable as the mine it is attached to. If ore grades disappoint, if the mine operator runs into permitting problems, or if commodity prices collapse and the operator suspends production, the stream simply stops delivering metal. The upfront payment is gone, the cash flows stop, and the streaming company is left as an unsecured creditor fighting for position in whatever restructuring follows.
Jurisdictional risk layers on top of operational risk. Silver mines are concentrated in Latin America – Mexico, Peru, and Bolivia collectively account for a substantial share of global primary silver production. Each of those countries carries its own set of political, regulatory, and royalty-regime risks. A change in mining tax law, a community blockade, or an abrupt shift in government policy toward foreign capital can impair a stream agreement regardless of how carefully it was originally structured. Pension funds with strict ESG mandates face an additional complication: many silver mines produce the metal as a byproduct of lead, zinc, or copper operations, and those base-metal operations carry environmental footprints that require their own diligence.
Silver price volatility is a more mundane but still real concern. The embedded margin in a streaming agreement provides a buffer, but if spot silver falls sharply and stays low for an extended period, the fund’s mark-to-market exposure on its streaming vehicle or listed equity position can create tracking problems against liability benchmarks. Silver’s price has historically moved in a wider range than gold relative to its starting price, reflecting thinner markets and the influence of speculative futures positioning. A pension fund that bought into a streaming structure partly on the inflation-hedge narrative could find itself holding an asset that behaves more like a risk asset than a defensive one during a broad market sell-off.
There is also a concentration problem building at the market level. If institutional capital continues flowing into streaming structures in volume, the upfront pricing of new streams will compress, reducing the margin advantage that made these agreements attractive in the first place. The streaming market has historically been dominated by a handful of large players, and their competitive moat has rested partly on having a lower cost of capital than junior miners could access elsewhere. Pension fund capital, which is both abundant and patient, narrows that moat – which is good for miners seeking financing but gradually erodes the return profile for the funds arriving latest to the structure.
Frequently Asked Questions
What is a silver streaming agreement?
A silver streaming agreement lets an investor pay an upfront fee to a mining company in exchange for the right to buy silver at a fixed below-market price for the life of the mine.
Why are pension funds interested in silver streams?
Silver streams offer long-duration cash flows, inflation sensitivity, and margins insulated from mining cost inflation – qualities that align well with pension fund liability structures.