Pension Funds Quietly Build Exposure to Ethanol Pipeline Throughput Agreements

The Quiet Pivot Into Ethanol Infrastructure
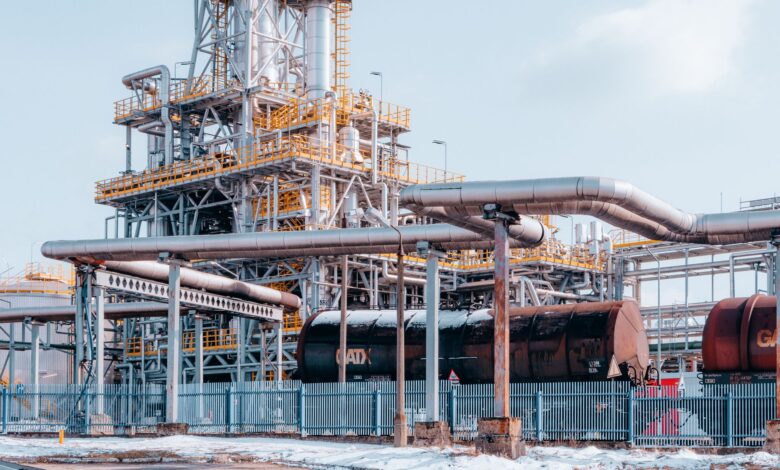
Pension funds managing retirement assets for teachers, municipal workers, and public employees have been steadily building positions in a corner of the energy market most investors overlook entirely: ethanol pipeline throughput agreements. These contracts – long-term arrangements that guarantee a fixed volume of ethanol will move through a pipeline over a set period – generate predictable, fee-based income that looks attractive against the backdrop of volatile equity markets and stubbornly low yields on traditional fixed-income allocations.
The appeal is structural. Unlike equity stakes in ethanol producers, which rise and fall with corn prices and refining margins, throughput agreements are paid regardless of whether the commodity price moves up or down. The pipeline operator collects a fee per gallon transported, and the pension fund, as a holder of that agreement or a debt instrument secured by it, receives a contractually defined cash flow. It is the toll-road model applied to liquid fuel logistics.
This is not a trend announced in press releases.
Why Throughput Agreements Attract Long-Duration Capital
The duration profile of these agreements makes them a natural fit for pension liabilities. A public pension fund often needs to match assets to obligations stretching 20 to 40 years into the future. An ethanol throughput agreement with a 15- or 20-year term, backed by an investment-grade counterparty such as a major fuel blender or agricultural cooperative, offers the kind of duration that corporate bonds rarely provide without taking on significant credit risk. The cash flows are inflation-sensitive in some structures, with volume guarantees tied to federally mandated Renewable Fuel Standard (RFS) blending obligations, which creates a degree of regulatory backstop that pure commodity contracts lack.
The Renewable Fuel Standard is central to understanding why these agreements carry lower demand risk than they might appear to. Federal blending mandates require a certain volume of ethanol to be mixed into the gasoline supply each year. That mandate does not disappear when corn prices spike or when crude oil trades below production cost. Pipelines that carry ethanol from Midwest production facilities to Gulf Coast or East Coast blending terminals are therefore handling a volume of product that has a regulatory floor beneath it. Pension fund managers structuring exposure around that floor are, in effect, treating the RFS as a long-duration fixed-income anchor.
The mechanics of how pension funds access these agreements vary. Some take direct stakes in pipeline operating companies through infrastructure fund vehicles. Others purchase project finance debt secured by a specific throughput contract, meaning their claim is against the cash flows of a single pipeline segment rather than a diversified corporate entity. A smaller number of the largest public pension systems have participated in bilateral negotiations with pipeline operators to co-finance capacity expansions in exchange for preferred revenue positions – agreements that rarely surface in public filings until regulatory disclosure requirements force them to.
The Risk Calculus That Most Allocators Miss
The risks embedded in ethanol throughput agreements are real and not always obvious to allocators more familiar with traditional infrastructure like toll roads or airports. Counterparty concentration is the first concern: if the agreement is guaranteed by a single large agricultural cooperative or regional fuel distributor, the pension fund’s income depends entirely on that entity’s financial health. Unlike a broad corporate bond portfolio, there is no diversification within a single throughput contract. A counterparty that runs into financial stress – as several regional ethanol producers have during prolonged corn price shocks – can trigger renegotiation pressure even on contracts that appear iron-clad on paper.
Policy risk is the second layer. The Renewable Fuel Standard has faced repeated legal and political challenges since its expansion under the Energy Independence and Security Act. Small refinery exemptions, which the Environmental Protection Agency has granted inconsistently across different administrations, reduce the effective blending mandate and therefore reduce the throughput volumes that pipelines need to move. A pension fund holding a throughput agreement that assumed maximum RFS compliance finds its cash flow projections under pressure when waiver activity increases. The agreement does not break – but the economics become less attractive, and secondary market liquidity for these instruments is thin enough that exiting is not straightforward.
There is also a longer-term question about the role of liquid ethanol in the fuel mix as electric vehicle adoption changes gasoline consumption patterns over the next decade and beyond. Throughput agreements written for 20-year terms today carry a tail-end risk that is genuinely difficult to price. The pension funds taking these positions are, at least implicitly, making a bet that liquid fuel infrastructure remains relevant through the 2040s – a reasonable view, but not a certainty. This is also a space where sovereign wealth funds have been building exposure in adjacent liquid fuel infrastructure, suggesting that institutional capital broadly is leaning toward long-duration energy logistics as a distinct asset class.
What This Signals for Infrastructure Allocations
The growing interest from pension capital in ethanol throughput agreements points to a broader compression of the opportunity set in traditional infrastructure. Airports, toll roads, and regulated utilities have been bid up by a decade of institutional capital inflows, and the yield premium that made them attractive has thinned considerably. Pension fund managers under pressure to hit actuarial return targets – typically in the range of 6.5 to 7.5 percent annually for U.S. public funds – are moving further along the complexity spectrum to find spread. Ethanol pipeline throughput agreements sit in a zone where the counterparties are creditworthy, the regulatory framework is established, and the deal structures are well understood by infrastructure lawyers and project finance lenders, but where most generalist allocators have not yet followed. That gap is exactly what makes the current moment attractive to the funds moving early, and exactly what closes as more capital chases the same contracts.