
The Quiet Accumulation
Sovereign wealth funds don’t announce their intentions. They file paperwork, move capital through layered structures, and by the time a trend becomes visible to the broader market, the position has already been built. That pattern is now playing out with manganese royalty streams – a niche corner of the commodities market that has attracted serious institutional attention over the past two years, largely away from public view.
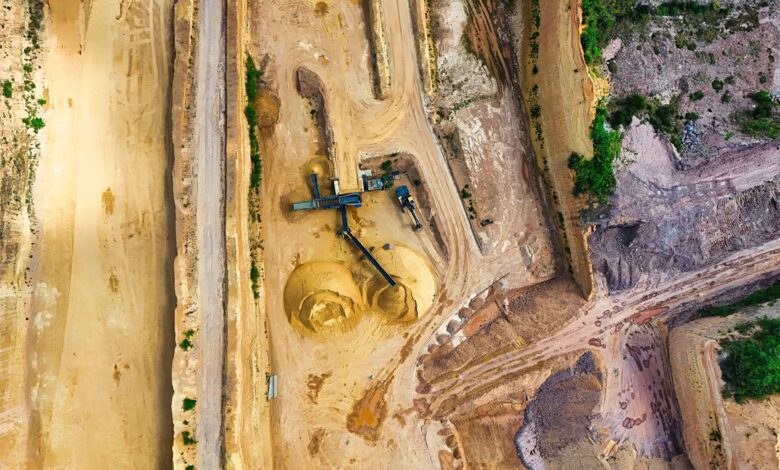
Manganese sits at the intersection of two powerful demand forces: steel production, which consumes roughly 90 percent of global manganese supply, and the growing battery market, where high-purity manganese is a key input for certain lithium-ion chemistries. Royalty structures built on top of manganese mining operations allow institutions to collect a percentage of revenue or production without taking on the operational risk of running a mine. For funds managing hundreds of billions in assets, that combination of commodity exposure with reduced downside risk is exactly the kind of structure they have been moving toward across the broader mining sector.
Why Royalty Streams, Why Now
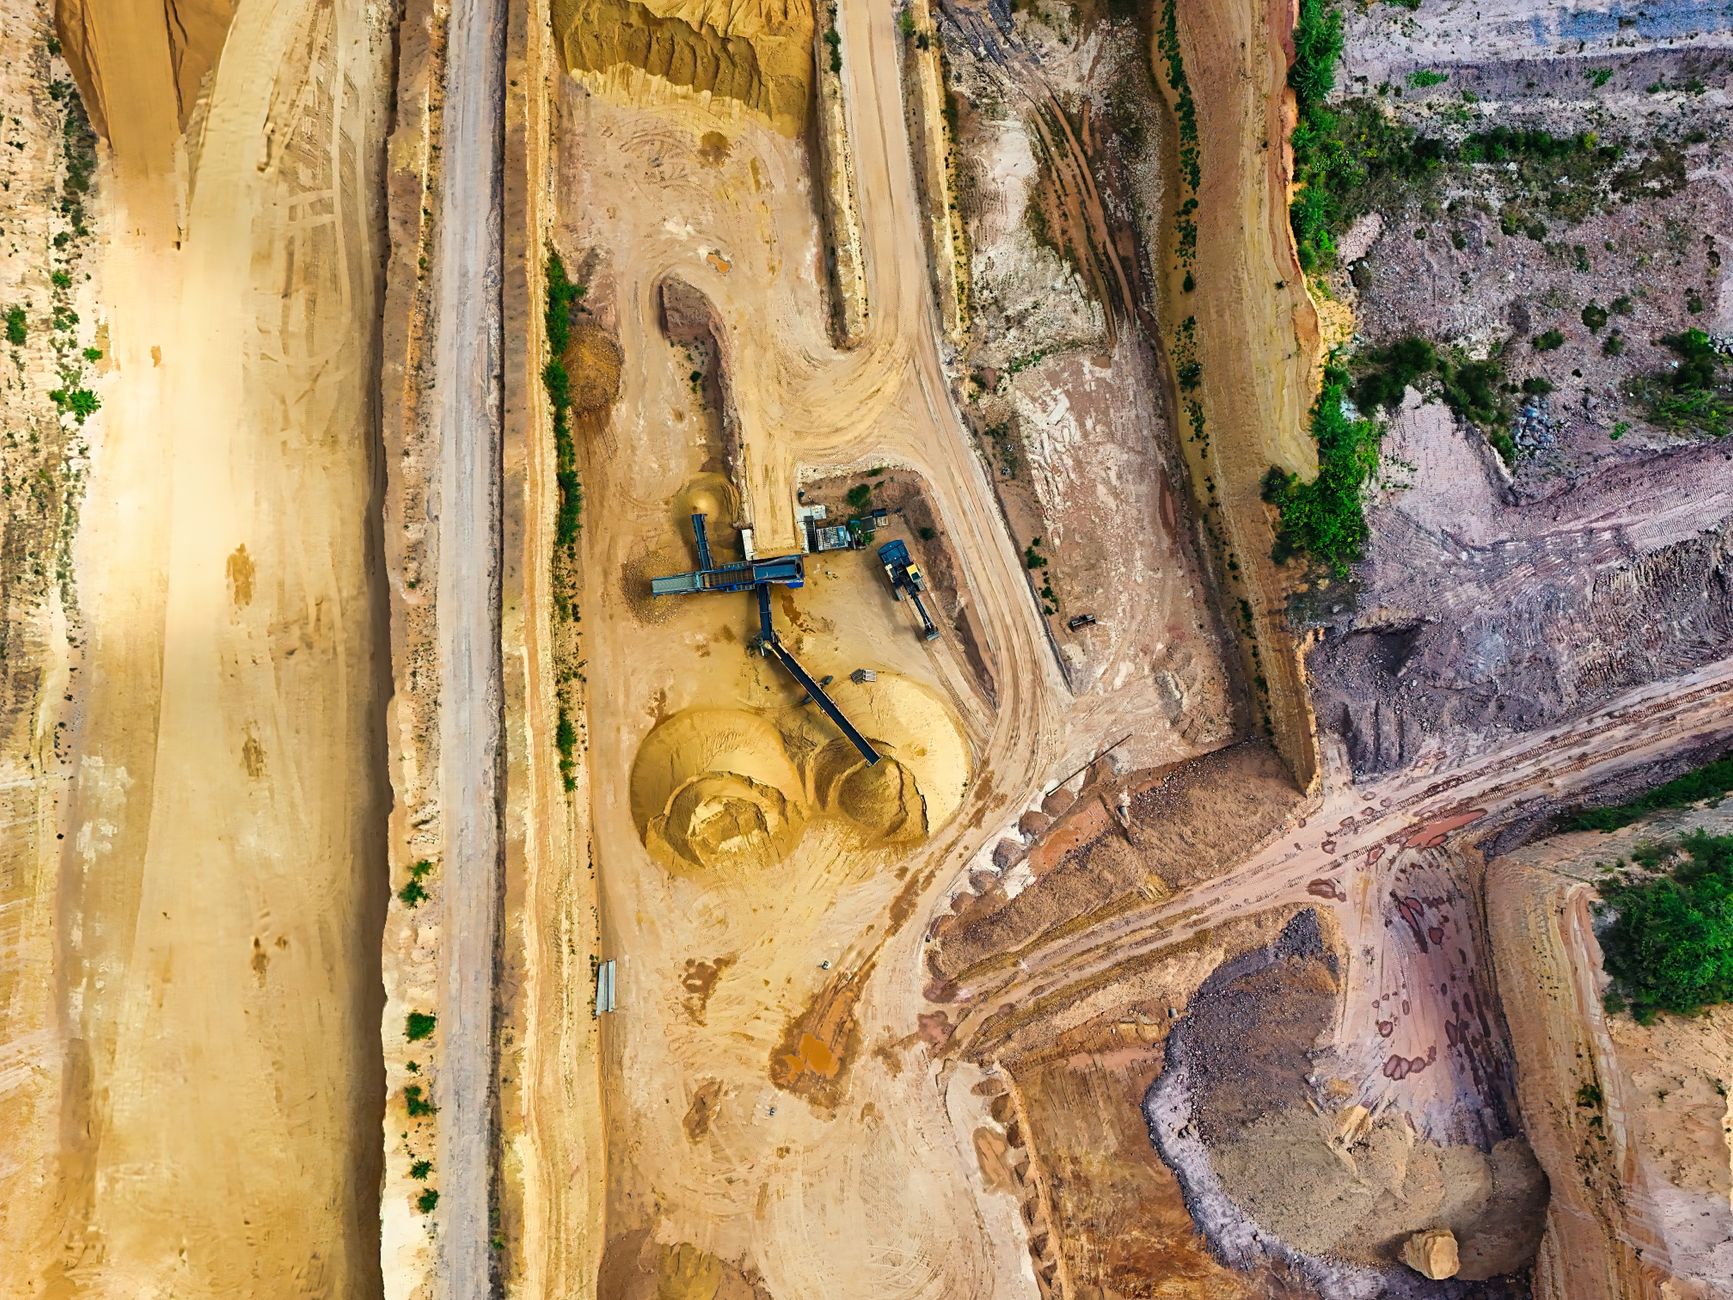
The royalty and streaming model has been a fixture in gold and silver markets for decades, with companies like Franco-Nevada and Royal Gold building substantial businesses around the concept. The extension of that model into battery-adjacent metals is newer, and manganese is among the commodities seeing the most structured activity. A royalty agreement typically grants the holder a percentage of production or gross revenue from a mine for the life of the asset, in exchange for an upfront capital payment. The mining operator gets financing without diluting equity; the royalty holder gets long-duration commodity exposure.
For sovereign wealth funds, the long-duration aspect is particularly attractive. These are institutions with 30- to 50-year investment horizons, managing capital for future generations rather than quarterly returns. A royalty stream tied to a producing manganese mine in South Africa or Gabon – the two countries that dominate global supply – can generate cash flows for decades. The structure also sidesteps the political and logistical risks of direct mine ownership, which matters when the host countries involved have complex regulatory environments.
The battery angle adds a layer of optionality that makes the asset more interesting than a simple steel-market play. If high-purity manganese demand accelerates alongside electric vehicle adoption, royalty holders benefit automatically without having to make additional capital investments. The mine operator bears the cost of upgrading processing capabilities; the royalty stream simply captures a share of whatever revenue results. That asymmetry – participating in upside without funding the operations that generate it – is precisely why institutional capital has been patient enough to build these positions quietly rather than through splashy acquisitions.
The Structural Appeal for Long-Term Capital
Sovereign wealth funds have been building royalty exposure across multiple mining sectors, and the logic is consistent regardless of the underlying commodity. Royalties behave differently from equity stakes in mining companies. They don’t dilute when the operator raises capital, they don’t absorb cost overruns, and they don’t require the institutional investor to have operational mining expertise. What they require is patience, capital, and the legal infrastructure to enforce the agreement across jurisdictions and across decades.
Manganese specifically offers something that some other battery metals don’t: scale. The manganese market is large enough that meaningful royalty positions can be built without immediately moving prices or attracting regulatory scrutiny. Lithium and cobalt, by comparison, are smaller markets where large institutional moves are harder to execute quietly. Manganese production is also geographically concentrated, which means a small number of royalty agreements can provide significant exposure to the global supply picture.
The counterargument is that manganese prices have historically been volatile and that the battery demand thesis, while real, depends on specific battery chemistries maintaining market share against competing technologies. Lithium iron phosphate batteries, which have surged in adoption particularly in China, use no manganese. If that chemistry continues to dominate, the premium attached to manganese’s battery-grade applications shrinks. Sovereign wealth funds building royalty positions now are betting that manganese’s role in next-generation battery designs – particularly LMFP and high-voltage chemistries – is durable enough to justify long-duration commitments.
The mechanics of how these funds actually acquire royalty streams vary considerably. Some invest directly in royalty companies, taking minority stakes in firms that have already assembled portfolios of agreements. Others negotiate directly with mining operators, particularly for assets where the operator needs capital and has limited access to conventional financing. A smaller number work through specialized private credit structures that blend royalty economics with debt features, giving the fund priority in repayment while preserving commodity upside. Each approach carries different liquidity profiles and risk characteristics, which is why the positioning tends to be spread across multiple vehicles rather than concentrated in a single entry point.
What the pattern suggests, when viewed across funds and geographies, is a deliberate effort to build commodity exposure that doesn’t show up in standard portfolio reporting the way an equity stake would. Royalty streams are often classified as alternative assets or private credit, depending on the structure used, which means the aggregate positioning in manganese across sovereign wealth funds globally is almost certainly larger than any public disclosure would indicate. The question isn’t whether this capital is moving into the sector – the deal activity makes that clear enough – it’s whether the battery demand thesis that underlies the premium valuation holds over the decades these agreements are designed to run.