
The Quiet Land Beneath the Water
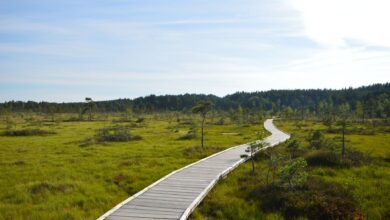
Peat bogs are not glamorous assets. They sit low in the landscape, waterlogged and often legally complicated, spanning regions of Scotland, Ireland, Scandinavia, Canada, and the Russian interior. For most of the past century, they were either harvested for fuel and horticultural use or simply left alone. Now a specific subset of family offices – those managing multigenerational wealth in the range of $500 million to several billion dollars – are moving quietly into a narrower and more obscure position: the water rights attached to these bogs.
The interest is not in the peat itself. It is in what peat bogs do hydrologically. A healthy bog acts as a sponge, absorbing rainfall and releasing water slowly into river systems below. The rights to that water flow, and the legal standing to control how it is used or allocated, are what family offices are beginning to acquire – through land purchases, easement agreements, and in some jurisdictions, direct licensing from regional water authorities.
Why Water Rights, and Why Now
Water rights as an asset class are not new. Agricultural operations in the American West have traded water entitlements for decades, and institutional capital has circulated around municipal water infrastructure for years. What is different about peat bog water rights is their scarcity logic. Peat bogs take thousands of years to form. Their hydrological function cannot be replicated quickly or artificially. Once degraded – through drainage for agriculture or commercial peat extraction – that water-regulating capacity is largely gone. That irreversibility is precisely the quality that long-horizon capital finds attractive.
Family offices, unlike public pension funds or quarterly-reporting hedge funds, can hold positions across decades without pressure to demonstrate near-term yield. Peat bog water rights produce little or no income today in most jurisdictions. Their value is positional: the bet is that water scarcity and regulatory frameworks around watershed protection will eventually make these rights enforceable and monetizable in ways that current law does not fully support. That gap between current utility and future legal recognition is where patient capital likes to sit.
The Mechanics of Acquisition
Acquiring peat bog water rights is not as simple as buying a parcel on an open market. In most European jurisdictions, water rights are tied to land ownership but regulated by national or regional environmental authorities. In the United Kingdom, for instance, the abstraction licensing system governs how much water can be drawn from any given source, and peat bogs fall under complex overlapping protections including Sites of Special Scientific Interest designations. Family offices entering this space typically work through specialist land agents and environmental solicitors rather than standard commercial real estate channels.
In Canada and parts of the United States, the legal framework is different but equally layered. Water rights in these regions are often governed by prior appropriation doctrines – first in time, first in right – or by riparian rights tied to adjacent land ownership. Some family offices have structured purchases of large tracts of boreal wetland in provinces like Quebec and Ontario, not primarily for timber or mineral value, but to establish riparian standing over the water systems those bogs feed into.
The financial structure of these positions varies. Some offices acquire full fee-simple ownership of bog land. Others negotiate long-term easements with existing landowners, paying annual fees in exchange for rights to the water flows without taking title to the underlying property. A smaller number have explored entering into conservation easement arrangements with land trusts, which generate tax benefits in exchange for permanent restrictions on development – a structure that simultaneously protects the asset’s hydrological function and reduces the holding cost.
Liquidity is the obvious constraint. There is no exchange where peat bog water rights trade. Secondary sales are private, negotiated, and infrequent. This illiquidity premium is baked into the thesis: the offices moving into this space are explicitly not looking for exit options on a five-year horizon. The position is intended to mature over twenty to forty years, with value unlocked either through direct commercial agreements with downstream water users, or through eventual government purchase programs tied to watershed restoration mandates.
The Regulatory Bet
The core wager embedded in this strategy is regulatory. Several European governments have committed to peatland restoration targets as part of their broader nature recovery and carbon sequestration obligations. The United Kingdom’s peat action plan, Scotland’s specific bog restoration funding, and the European Union’s Nature Restoration Law all create policy environments where private holders of bog-linked water rights may find themselves holding something governments need to buy access to or partner with.
Carbon is a secondary layer. Restored peat bogs sequester carbon at rates that qualify under voluntary carbon markets, and a number of family offices are structuring acquisitions to include future carbon credit streams alongside the water rights. This stacking of potential income sources – water rights plus carbon credits plus eventual conservation sale – is what makes the position financially coherent even without near-term cash flow. No single income stream needs to be large. The combination, across a long enough time horizon, is what generates the return profile these offices are underwriting.
What This Signals for Natural Asset Investing
The movement into peat bog water rights is part of a broader reorientation in how multigenerational capital thinks about natural assets. Rather than treating land as a vehicle for productive output – crops, timber, minerals – a growing number of family offices are acquiring land for what it holds back: water, carbon, biodiversity. The economic logic inverts the traditional model. Value accrues not from extraction but from preservation and the legal control that preservation confers.
This creates a quiet tension with conservation organizations, which have historically led peatland protection efforts. Some land trusts have begun to notice family office capital arriving in regions they have long considered their operational territory, sometimes outbidding non-profit buyers for key parcels. The relationship between private capital and conservation goals is not automatically adversarial – many family offices are genuinely aligned with restoration outcomes – but the question of who ultimately controls access to these hydrological systems, and on what terms, is one that water regulators in several countries have not yet been forced to answer at scale.
Positions are being built now, while those regulatory answers are still unwritten. By the time governments formalize the rules around peat bog water rights, some family offices will already hold the most strategically located assets in the relevant watersheds. Whether that constitutes prescient investing or regulatory arbitrage depends almost entirely on which side of the negotiating table you are sitting on when the frameworks finally arrive.