
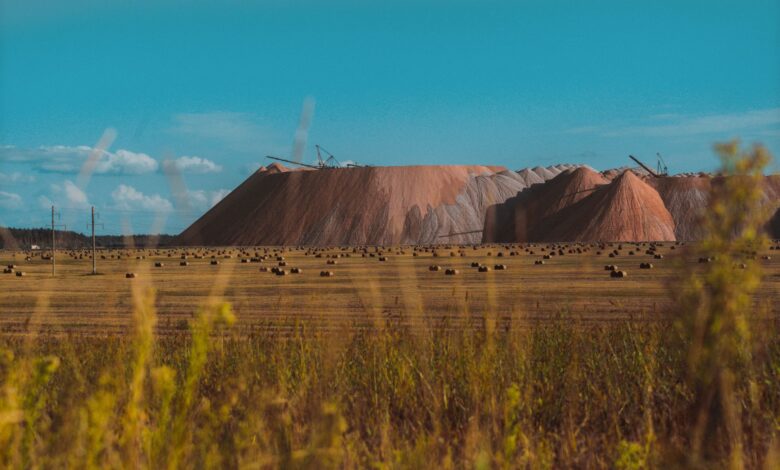
Sovereign wealth funds – the state-owned investment vehicles managing trillions of dollars on behalf of nations – have begun moving quietly into a corner of the commodities market that most institutional investors have overlooked: royalty streams tied to bauxite extraction. The positions are modest by sovereign fund standards, but the pattern is deliberate and accelerating.
Why Bauxite Royalties, Why Now
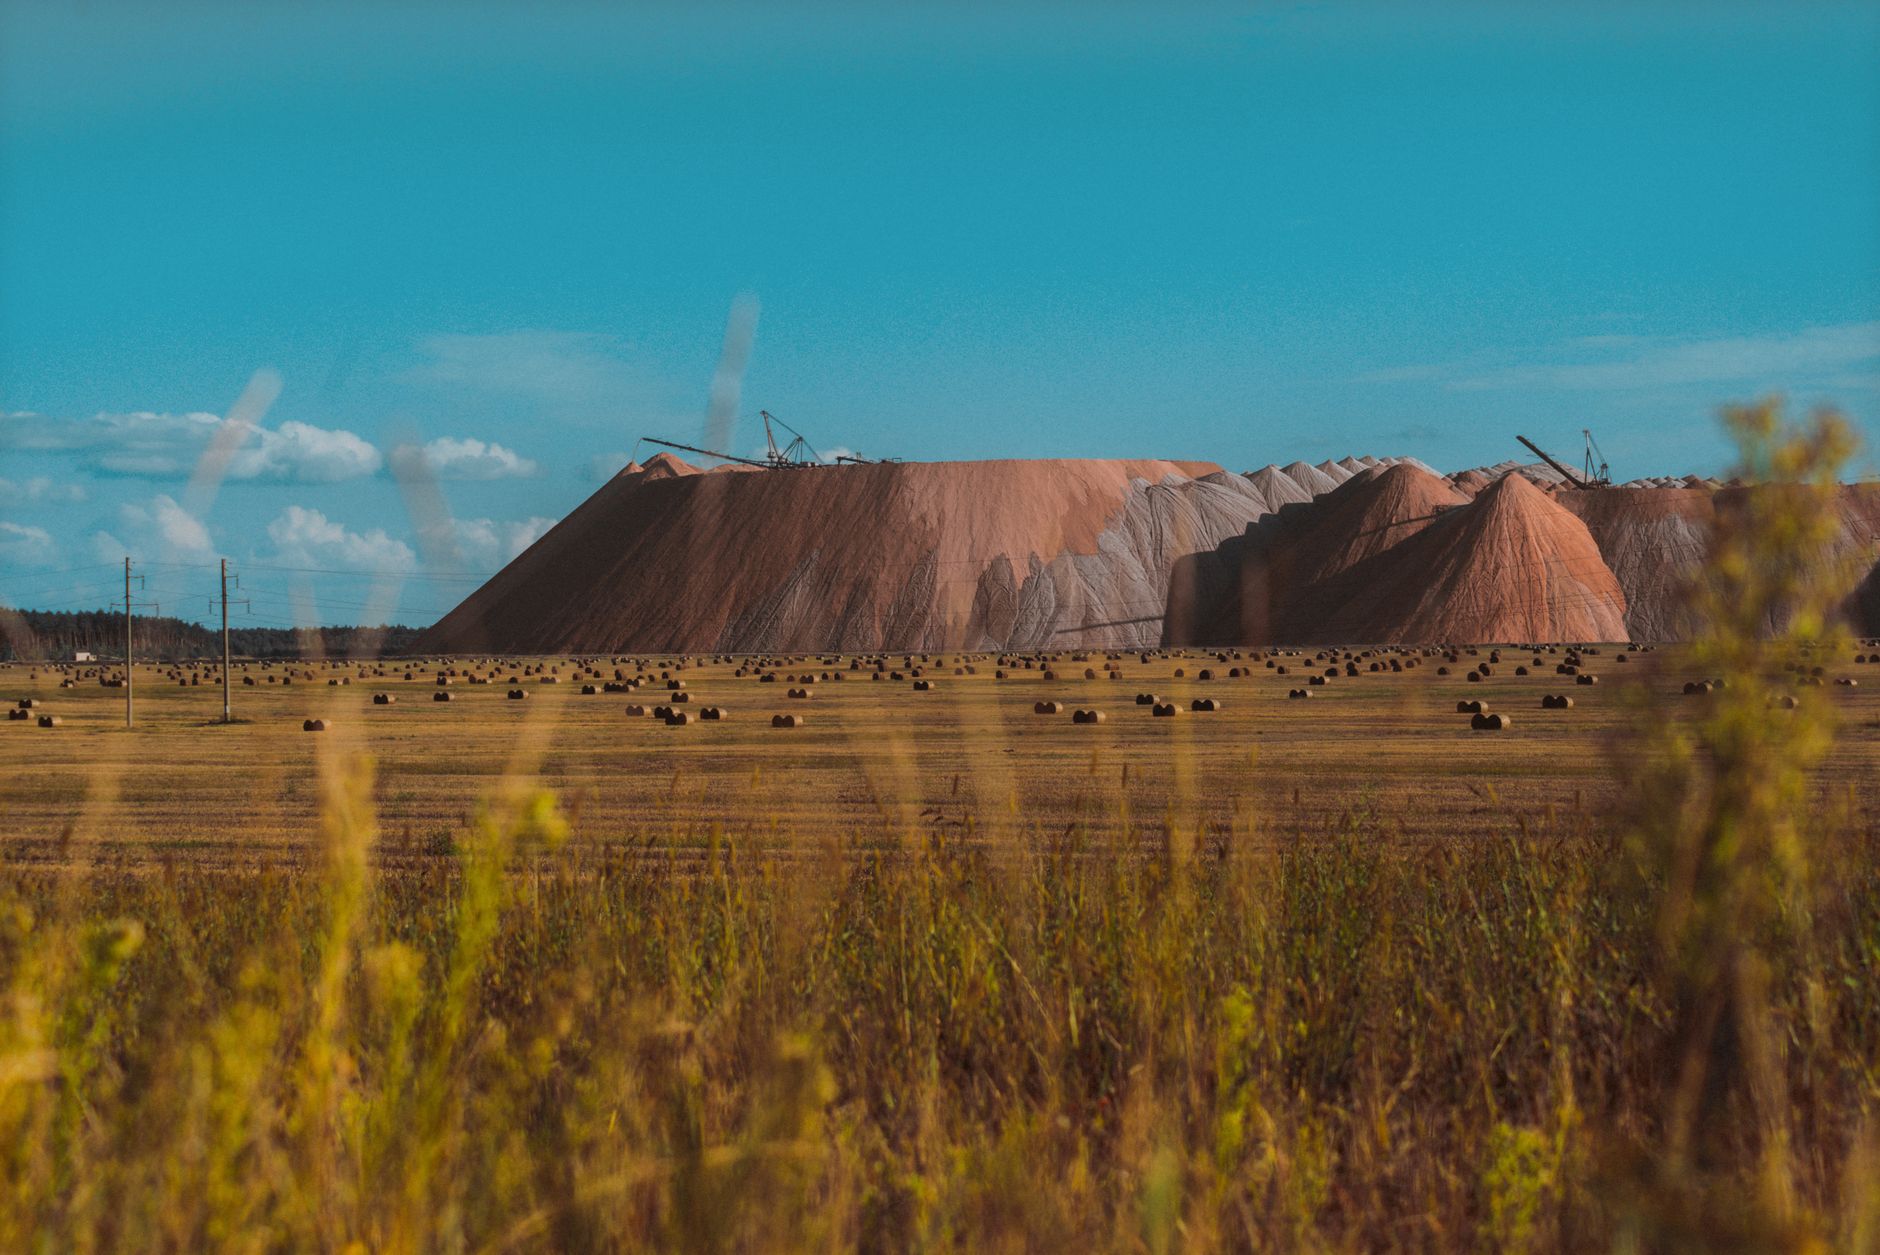
Bauxite is the primary ore from which aluminum is refined, and aluminum sits at the center of nearly every major industrial transition happening right now – from electric vehicle frames to aerospace components to the mounting hardware that holds solar panels in place. Demand projections for aluminum have been revised upward repeatedly over the past several years, and with that revision comes renewed interest in the upstream supply chain. Royalty streams, which pay a percentage of revenue from each tonne of bauxite extracted regardless of production costs, offer exposure to that demand without the capital expenditure and operational liability of running a mine.
The royalty model itself is not new. It has been common in gold and silver mining for decades, where streaming companies effectively act as silent financiers, providing upfront capital to miners in exchange for long-term royalty rights. What is relatively new is the application of that structure to bauxite, a commodity that has historically attracted less financial engineering than precious metals. The ore is cheaper per tonne, the extraction is less glamorous, and the end market – industrial aluminum – lacks the speculative appeal of gold. That relative obscurity is precisely the point for sovereign funds seeking long-duration assets with low correlation to public equity markets.
Several factors have converged to make this an attractive moment. First, bauxite reserves are geographically concentrated in ways that create structural pricing power. Guinea alone holds a substantial share of the world’s high-grade deposits, and Australia, Brazil, and Jamaica hold much of the remainder. Any disruption to supply from those regions – political, logistical, or environmental – tends to move the market quickly. Second, long-term offtake agreements between miners and aluminum smelters provide predictable revenue baselines that make royalty cash flows easier to model than most commodity investments. Third, and perhaps most telling, the energy transition has created a floor under aluminum demand that did not exist five years ago.
Sovereign funds from the Gulf region, Southeast Asia, and Scandinavia have each shown interest through different mechanisms. Some have acquired minority equity positions in royalty holding companies. Others have structured direct agreements with junior mining operators that carry royalty-like economics without being labeled as such. The lack of consistent disclosure requirements across jurisdictions makes precise tracking difficult, but the directionality is clear from deal flow and from conversations circulating within commodity finance circles.
The Structure of a Bauxite Royalty Deal
A bauxite royalty agreement typically grants the royalty holder a fixed percentage – often between 1.5% and 4% – of gross revenue from ore sold at the mine gate. The holder receives this payment for the life of the mine, which for large deposits can span 30 to 50 years. Unlike equity ownership in a mining company, the royalty holder has no obligation to fund exploration costs, environmental remediation, labor disputes, or infrastructure upgrades. The cash flows arrive as long as the mine produces.
From a sovereign fund’s perspective, that structure solves several problems at once. These funds manage money across multi-decade horizons, often with explicit mandates to preserve wealth for future generations. They need assets that generate returns independent of short-term market sentiment. A 40-year royalty on a producing bauxite mine in a stable jurisdiction offers exactly that kind of duration, and the underlying commodity exposure provides a natural inflation hedge. When aluminum prices rise, royalty revenues rise. When the cost of living rises, so does the cost of everything made with aluminum, which eventually feeds back into pricing upstream.
The sovereign fund entry into this space has also been shaped by the behavior of private equity and specialized royalty companies that pioneered the bauxite royalty structure. By watching how those earlier entrants constructed deals and managed counterparty risk, state-backed investors have learned how to negotiate more effectively. A key concern has always been the credit quality of the mining operator – if the company extracting the ore goes bankrupt, the royalty stream may be disrupted even though the ore is still in the ground. Sophisticated buyers now routinely attach their royalty rights to the mineral title itself rather than to the operator’s corporate entity, which provides a degree of protection that early deals often lacked.
Pricing a bauxite royalty is more art than science. Discount rates vary depending on the political risk of the host country, the grade and accessibility of the deposit, the existence of binding offtake agreements, and the regulatory stability of the royalty regime itself. Guinea, which has become one of the most important sources of high-grade bauxite globally, carries political risk premiums that buyers and sellers continue to negotiate around. Some sovereign funds have shown a preference for assets in Australia and Brazil precisely because regulatory frameworks there are more predictable, even if the royalty rates those assets command are somewhat lower as a result.
The secondary market for bauxite royalties remains thin compared to precious metals royalties, but that is changing. As more institutional capital enters the space, the infrastructure for trading and valuing these assets is being built out. Legal standardization of royalty agreements, improved geological disclosure, and the growing presence of financial intermediaries with bauxite-specific expertise are all reducing the friction that once kept larger pools of capital on the sidelines. The pattern is not unlike what happened in propane storage infrastructure a few years earlier, where illiquidity premiums attracted patient institutional capital before the broader market caught up.
What Sovereign Accumulation Signals for the Broader Market
When sovereign wealth funds move into an asset class quietly and consistently, it tends to compress the illiquidity premium over time. Other institutional investors – pension funds, endowments, large family offices – typically follow once the asset class has been de-risked by early sovereign entry. That dynamic has played out in infrastructure, in private credit, and in real assets broadly. Bauxite royalties appear to be following a similar path, with sovereign positioning acting as a form of validation that draws in the next wave of capital. The result, for those already holding positions, is likely to be meaningful appreciation as the discount rates applied to these cash flows tighten.
For investors still on the sidelines, the more difficult question is whether the window for attractive entry pricing is already closing. The earliest buyers of bauxite royalty streams acquired assets at discounts that reflected genuine uncertainty – about aluminum demand trajectories, about the reliability of royalty structures in mining-heavy jurisdictions, about whether a secondary market would ever develop. Those uncertainties have not disappeared entirely, but they have diminished enough that pricing has moved. Whether what remains is a fair return for the risks still present, or whether the market has overcorrected on optimism, is a question that each potential entrant has to answer for itself – and sovereign fund positioning alone does not settle it.
Frequently Asked Questions
What is a bauxite royalty stream?
A bauxite royalty stream grants the holder a percentage of revenue from ore extracted at a mine, paid over the life of the deposit without requiring the holder to fund operating or capital costs.
Why are sovereign wealth funds interested in bauxite royalties?
Bauxite royalties offer long-duration, inflation-linked cash flows with low correlation to public markets – characteristics that align well with sovereign funds’ multi-decade investment mandates.