
The Quiet Accumulation
Sovereign wealth funds, long associated with trophy real estate and blue-chip equities, are quietly redirecting portions of their alternative asset allocations toward an unlikely corner of the energy market: royalty streams tied to flare gas capture operations.
Why Flare Gas Royalties Are Attracting State Capital
Flare gas – the natural gas burned off at oil production sites when no pipeline infrastructure exists to capture it – has historically been treated as a waste byproduct. The practice of flaring releases methane and carbon dioxide into the atmosphere, drawing regulatory scrutiny across major producing regions including the Permian Basin, the Bakken, and the Niger Delta. What has changed is the economics of capture: compression technology, modular liquefaction units, and on-site power generation equipment have made it commercially viable to monetize gas that would otherwise burn at the wellhead.
The royalty structure itself is what makes this appealing to patient, long-duration capital. Rather than directly owning the capture infrastructure, a growing number of sovereign funds are acquiring royalty agreements that entitle them to a percentage of revenue from gas that operators bring to market. The capital is deployed upfront, the operational complexity stays with the producer, and the fund collects a income stream that is largely insulated from day-to-day operational risk. It is a structure that mirrors what hedge funds have pursued in crude oil royalty streams, though sovereign funds tend to hold positions across much longer time horizons.
The regulatory tailwind matters here. Flaring restrictions are tightening across the United States, Canada, Norway, and increasingly across African producing nations. When regulations force operators to capture rather than burn, the volume flowing through royalty agreements rises without any additional capital deployment by the royalty holder. A sovereign fund that secured a royalty position before a regulatory tightening cycle benefits automatically as compliance deadlines convert previously flared volumes into capturable – and billable – gas. That dynamic makes the asset class function almost like a regulatory arbitrage play embedded inside an energy royalty.
The counterparty profile also deserves attention. Flare gas royalty agreements are typically signed with established upstream operators – major independents or national oil companies – rather than with early-stage ventures. That counterparty quality is essential for funds managing assets on behalf of national governments, where reputational exposure and capital preservation matter as much as yield. The combination of contractual income, regulated tailwinds, and investment-grade counterparties is a rare alignment in alternative assets right now.
Structural Mechanics and the Investment Case
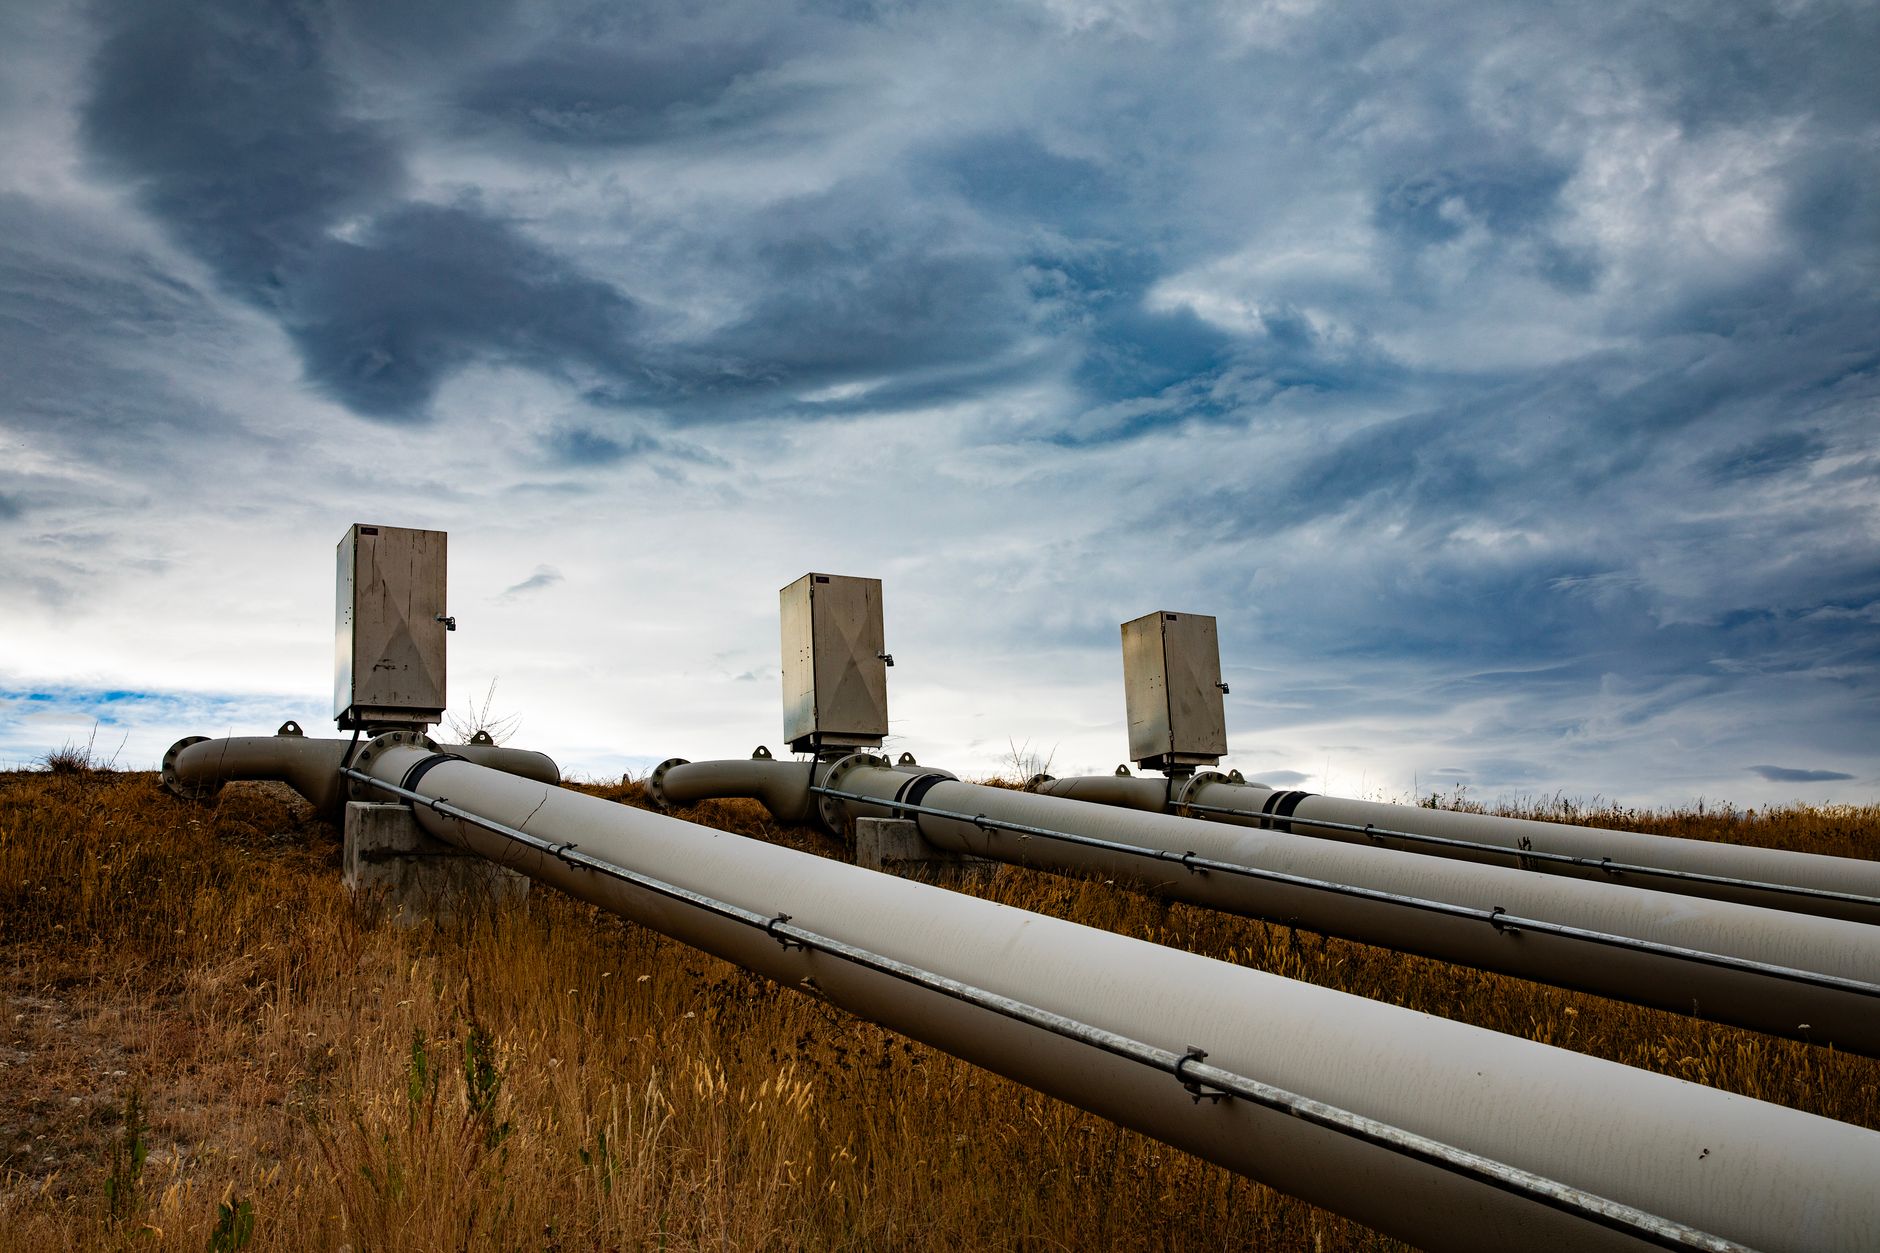
The mechanics of how these royalty streams are structured vary, but most follow a familiar template. A royalty company – sometimes a dedicated vehicle created specifically for this purpose – provides upfront capital to an oil and gas operator to fund the construction of gas capture and processing equipment. In return, it receives a perpetual or long-dated royalty on the net revenue generated by that captured gas. The royalty rate is negotiated at inception and can range from a low single-digit percentage to north of 20%, depending on the quality of the acreage and the volume projections. Sovereign funds are typically entering through secondary purchases of existing royalty agreements or through co-investment structures alongside specialized royalty platforms.
The yield profile is not dramatic by private equity standards, but that is precisely the point. Sovereign wealth funds managing intergenerational capital are not chasing 30% IRRs. They are looking for durable, inflation-linked income streams that do not require active management, do not correlate strongly with public equity markets, and generate cash flows measured in decades rather than years. Flare gas royalties, once a capture agreement is in place and the infrastructure is operational, tend to produce exactly that kind of steady, low-volatility income. Gas volumes from mature oil fields decline slowly and predictably, which makes cash flow modeling relatively straightforward.
There is also a carbon angle that some funds are beginning to quantify. Capturing gas that would otherwise be flared prevents methane emissions, and methane carries a global warming potential many times higher than carbon dioxide over a 20-year horizon. Some royalty holders are exploring whether the emissions prevented by their capital can be monetized through voluntary carbon markets or used to offset a fund’s own reported emissions. The accounting methodologies for this remain contested, and sovereign funds are generally cautious about overstating green credentials. But the optionality exists, and for funds with net-zero commitments to their domestic legislatures, the ability to point to tangible methane reduction is not nothing.
Geography is a critical variable. The Permian Basin in West Texas currently flares a substantial volume of associated gas, and regulatory pressure from the Environmental Protection Agency and the Texas Railroad Commission is pushing operators toward faster capture timelines. That regulatory pressure converts directly into higher royalty-eligible volumes. The Bakken formation in North Dakota has a longer history of flaring controversy and has already seen meaningful reduction, meaning the royalty volumes there are more established but growth is slower. International markets – particularly Nigeria and Algeria – offer larger flaring volumes but introduce sovereign risk, currency risk, and contract enforcement uncertainty that narrows the universe of sovereign funds willing to participate.
The entry price for these positions has risen as the strategy has attracted more attention. Early movers who built royalty portfolios five or six years ago are sitting on significant unrealized gains as competing capital from insurance general accounts, endowments, and now sovereign funds has compressed yields. A royalty stream that traded at a six or seven times revenue multiple a few years ago is now changing hands closer to ten or twelve times. That compression does not make the asset class unattractive, but it does mean the most straightforward arbitrage has narrowed, and new entrants are being more selective about acreage quality and operator reliability.
What This Signals for Energy Transition Capital
Sovereign fund interest in flare gas royalties signals something specific about how the largest pools of patient capital are approaching the energy transition: not as an all-or-nothing pivot away from hydrocarbons, but as a series of targeted bets on assets that generate income and reduce environmental harm simultaneously. Flare gas capture does not replace renewable energy investment – most sovereign funds are scaling both simultaneously – but it produces returns that wind and solar at current valuations often cannot match on a risk-adjusted basis.
The structural question that remains unresolved is what happens to these royalty streams as global oil production eventually declines. Associated gas production is tied directly to oil output, and if the long-term trajectory of oil demand is downward, the volumes supporting flare gas royalties will follow. Funds underwriting 30-year royalty agreements today are making an implicit bet that oil production remains robust through at least the 2040s – a forecast that is reasonable but not guaranteed, and one that differs meaningfully from fund to fund depending on which production decline models they find credible.
Frequently Asked Questions
What is a flare gas royalty stream?
A flare gas royalty stream is a contractual entitlement to a percentage of revenue generated when captured flare gas is brought to market, typically funded by upfront capital provided to an oil and gas operator.
Why are sovereign wealth funds interested in flare gas royalties?
The appeal lies in durable, low-volatility income, investment-grade counterparties, and regulatory tailwinds that convert previously flared volumes into royalty-eligible production without additional capital deployment.